Foundational assessment satisfaction is essential before initiating penalty for cash receipt of immovable-property sale consideration under section 27...
Tax collection at source on purchases removes duplicate withholding obligation, while trade-creditor evidence requires verification before unexplained...
Transfer-pricing comparability requires material turnover effects; adjustments must cover only associated-enterprise transactions and exclude abnormal...
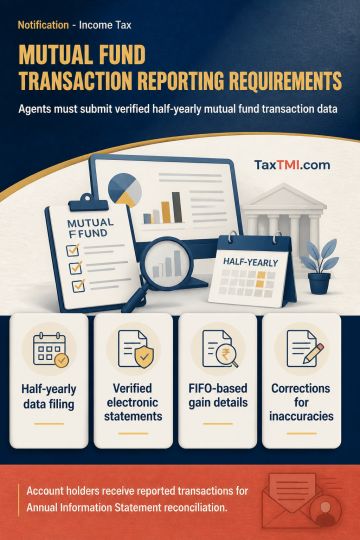
Registrar and Share Transfer Agents registered under the SEBI Act must furnish half-yearly Statements of Financial Transactions for mutual fund transactions in the prescribed electronic format, with a signed and verified control statement. Reporting supports pre-filling of income-tax returns and requires account holders to receive reported transaction information for reconciliation with the Annual Information Statement. Transaction summaries must cover user-initiated debit transactions, apply FIFO to identify corresponding acquisitions and determine holding periods, and classify assets as short-term or long-term under the prescribed security classes. Estimated sale consideration, acquisition cost, grandfathered cost rules and indexation must be reported where applicable. Invalid files are rejected; inaccuracies, defects and deletions require correction or deletion statements. Reporting entities must maintain information-security, archival and retrieval procedures.
Registrar and Share Transfer Agents registered under the SEBI Act must furnish half-yearly Statements of Financial Transactions for mutual fund transactions in the prescribed electronic format, with a signed and verified control statement. Reporting supports pre-filling of income-tax returns and requires account holders to receive reported transaction information for reconciliation with the Annual Information Statement. Transaction summaries must cover user-initiated debit transactions, apply FIFO to identify corresponding acquisitions and determine holding periods, and classify assets as short-term or long-term under the prescribed security classes. Estimated sale consideration, acquisition cost, grandfathered cost rules and indexation must be reported where applicable. Invalid files are rejected; inaccuracies, defects and deletions require correction or deletion statements. Reporting entities must maintain information-security, archival and retrieval procedures.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881