Business expenditure and depreciation rules allow operational outgoings while limiting disallowances for personal elements and unsupported third-party...
Compromise-and-arrangement extensions may accommodate debt assignment where creditor commercial judgment supports value maximisation and avoids proced...
Delayed-payment surcharge is not taxable tolerance consideration where it penalises default, while meter testing follows electricity distribution trea...
Page of 4886
Press 'Enter' after typing page number.
861 to 880 of 97705 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
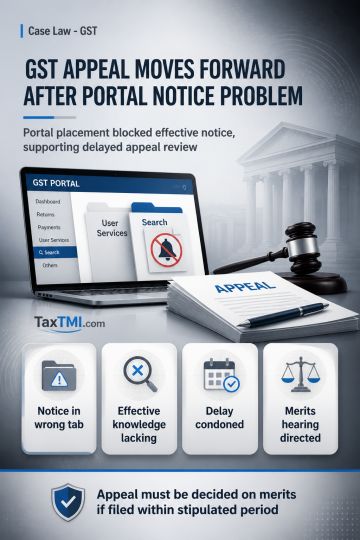
Sufficient cause supported condonation of delay in a GST appeal where the taxpayer lacked effective knowledge of the show-cause notice and adjudication order because they were uploaded under a non-designated portal tab. Although the Appellate Authority remained bound by the limitation prescribed under section 107 of the RGST/CGST Act, circumstances beyond the taxpayer's control and the risk of grave prejudice justified merits review. The delay was condoned, with a direction to entertain and decide the appeal on merits if filed within the stipulated period.
Sufficient cause supported condonation of delay in a GST appeal where the taxpayer lacked effective knowledge of the show-cause notice and adjudication order because they were uploaded under a non-designated portal tab. Although the Appellate Authority remained bound by the limitation prescribed under section 107 of the RGST/CGST Act, circumstances beyond the taxpayer's control and the risk of grave prejudice justified merits review. The delay was condoned, with a direction to entertain and decide the appeal on merits if filed within the stipulated period.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4886