Foundational assessment satisfaction is essential before initiating penalty for cash receipt of immovable-property sale consideration under section 27...
Tax collection at source on purchases removes duplicate withholding obligation, while trade-creditor evidence requires verification before unexplained...
Transfer-pricing comparability requires material turnover effects; adjustments must cover only associated-enterprise transactions and exclude abnormal...
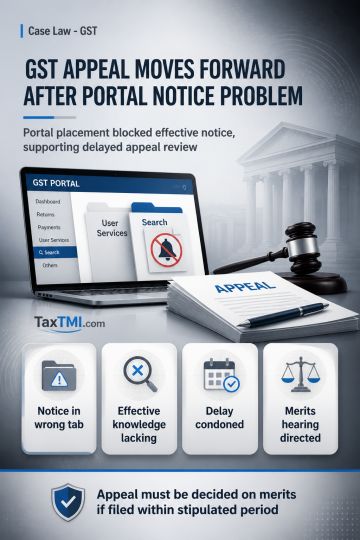
Sufficient cause supported condonation of delay in a GST appeal where the taxpayer lacked effective knowledge of the show-cause notice and adjudication order because they were uploaded under a non-designated portal tab. Although the Appellate Authority remained bound by the limitation prescribed under section 107 of the RGST/CGST Act, circumstances beyond the taxpayer's control and the risk of grave prejudice justified merits review. The delay was condoned, with a direction to entertain and decide the appeal on merits if filed within the stipulated period.
Sufficient cause supported condonation of delay in a GST appeal where the taxpayer lacked effective knowledge of the show-cause notice and adjudication order because they were uploaded under a non-designated portal tab. Although the Appellate Authority remained bound by the limitation prescribed under section 107 of the RGST/CGST Act, circumstances beyond the taxpayer's control and the risk of grave prejudice justified merits review. The delay was condoned, with a direction to entertain and decide the appeal on merits if filed within the stipulated period.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881