Effective hearing in GST adjudication requires actual opportunity to respond; ineffective service through a former auditor invalidated ex parte procee...
Third-party search material requires special assessment route, rendering general reassessment notices without jurisdiction when it forms the proceedin...
Transfer-pricing adjustments must be confined to international associated-enterprise transactions, while functionally dissimilar comparables remain ex...
Insolvency moratorium bars income-tax revision proceedings against corporate debtors until the moratorium ends, preserving merits for later determinat...
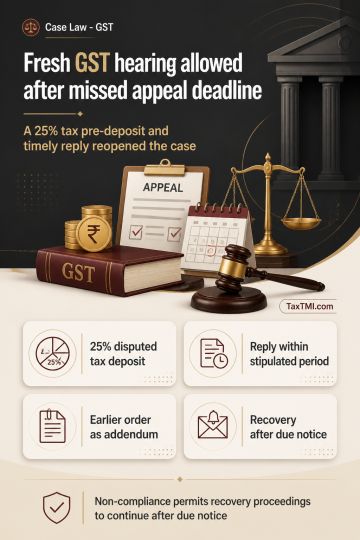
Fresh adjudication was permitted where the petitioner had not participated in the original proceedings and the statutory appellate limitation had expired. The impugned order was quashed, subject to an additional pre-deposit of 25% of the disputed tax and submission of a reply to the show-cause notice within the stipulated period. The earlier order was to operate as an addendum to the show-cause notice for the fresh proceedings. No further extension or concession was available; failure to comply allowed recovery proceedings to continue in accordance with law after due notice.
Fresh adjudication was permitted where the petitioner had not participated in the original proceedings and the statutory appellate limitation had expired. The impugned order was quashed, subject to an additional pre-deposit of 25% of the disputed tax and submission of a reply to the show-cause notice within the stipulated period. The earlier order was to operate as an addendum to the show-cause notice for the fresh proceedings. No further extension or concession was available; failure to comply allowed recovery proceedings to continue in accordance with law after due notice.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881