Foundational assessment satisfaction is essential before initiating penalty for cash receipt of immovable-property sale consideration under section 27...
Tax collection at source on purchases removes duplicate withholding obligation, while trade-creditor evidence requires verification before unexplained...
Transfer-pricing comparability requires material turnover effects; adjustments must cover only associated-enterprise transactions and exclude abnormal...
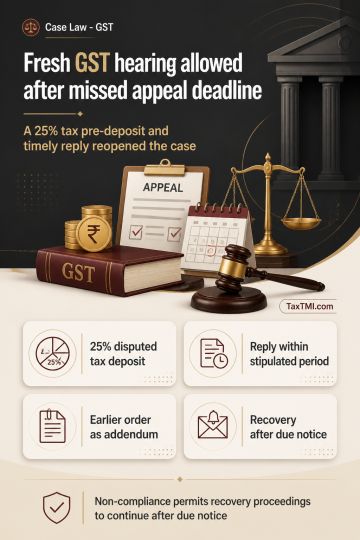
Fresh adjudication was permitted where the petitioner had not participated in the original proceedings and the statutory appellate limitation had expired. The impugned order was quashed, subject to an additional pre-deposit of 25% of the disputed tax and submission of a reply to the show-cause notice within the stipulated period. The earlier order was to operate as an addendum to the show-cause notice for the fresh proceedings. No further extension or concession was available; failure to comply allowed recovery proceedings to continue in accordance with law after due notice.
Fresh adjudication was permitted where the petitioner had not participated in the original proceedings and the statutory appellate limitation had expired. The impugned order was quashed, subject to an additional pre-deposit of 25% of the disputed tax and submission of a reply to the show-cause notice within the stipulated period. The earlier order was to operate as an addendum to the show-cause notice for the fresh proceedings. No further extension or concession was available; failure to comply allowed recovery proceedings to continue in accordance with law after due notice.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881