Credit-note turnover adjustments preserve inverted-duty refunds, while ministerial re-computation does not constitute an impermissible appellate reman...
Revisional jurisdiction over export quota premium deductions requires both error and Revenue prejudice; a permissible assessment view cannot be displa...
Page of 4881
Press 'Enter' after typing page number.
501 to 520 of 97618 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
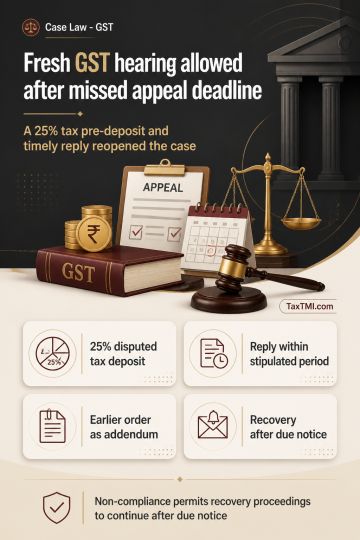
Fresh adjudication was permitted where the petitioner had not participated in the original proceedings and the statutory appellate limitation had expired. The impugned order was quashed, subject to an additional pre-deposit of 25% of the disputed tax and submission of a reply to the show-cause notice within the stipulated period. The earlier order was to operate as an addendum to the show-cause notice for the fresh proceedings. No further extension or concession was available; failure to comply allowed recovery proceedings to continue in accordance with law after due notice.
Fresh adjudication was permitted where the petitioner had not participated in the original proceedings and the statutory appellate limitation had expired. The impugned order was quashed, subject to an additional pre-deposit of 25% of the disputed tax and submission of a reply to the show-cause notice within the stipulated period. The earlier order was to operate as an addendum to the show-cause notice for the fresh proceedings. No further extension or concession was available; failure to comply allowed recovery proceedings to continue in accordance with law after due notice.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881