Mandatory textile export qualifiers distinguish flame-retardant fabrics from other listed fabrics for automated identification under the textiles ince...
Personal liberty safeguards restrict arrest after court-directed GST appearance, requiring interim release where authorities overreach pending proceed...
Alternative statutory remedy and delay bar GST writ challenges despite pending rectification, while distinct subject matter permits parallel proceedin...
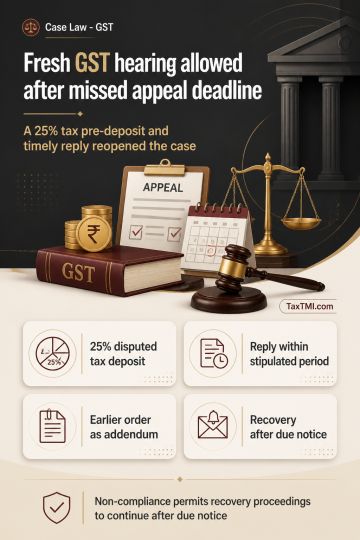
Fresh adjudication was permitted where the petitioner had not participated in the original proceedings and the statutory appellate limitation had expired. The impugned order was quashed, subject to an additional pre-deposit of 25% of the disputed tax and submission of a reply to the show-cause notice within the stipulated period. The earlier order was to operate as an addendum to the show-cause notice for the fresh proceedings. No further extension or concession was available; failure to comply allowed recovery proceedings to continue in accordance with law after due notice.
Fresh adjudication was permitted where the petitioner had not participated in the original proceedings and the statutory appellate limitation had expired. The impugned order was quashed, subject to an additional pre-deposit of 25% of the disputed tax and submission of a reply to the show-cause notice within the stipulated period. The earlier order was to operate as an addendum to the show-cause notice for the fresh proceedings. No further extension or concession was available; failure to comply allowed recovery proceedings to continue in accordance with law after due notice.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4886