Reassessment for unreturned property sales survives where transfer information, non-filing, and unsupported exemption claims establish a prima facie l...
Profit-element taxation limits additions for unaccounted flat-sale receipts and grey-market purchases, while reliable search records support partial a...
Non-participating bidders cannot disturb concluded liquidation sales on speculative prejudice, while costs for such challenges must remain proportiona...
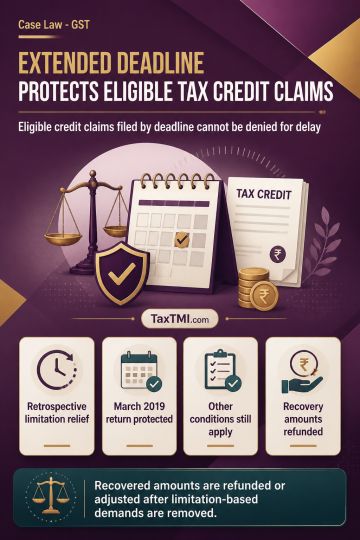
Retrospectively inserted section 16(5) extends the time for eligible registered persons to claim input tax credit for specified financial years where the section 39 return was filed by 30 November 2021. It overrides the limitation in section 16(4) for claims falling within that extended period, while preserving the requirement to satisfy all other statutory conditions. Input tax credit claimed through a March 2019 return filed within the extended deadline cannot be denied solely for delay. Limitation-based disallowance, consequential recovery, and related demands are to be removed, with recovered amounts refunded or adjusted against future tax.
Retrospectively inserted section 16(5) extends the time for eligible registered persons to claim input tax credit for specified financial years where the section 39 return was filed by 30 November 2021. It overrides the limitation in section 16(4) for claims falling within that extended period, while preserving the requirement to satisfy all other statutory conditions. Input tax credit claimed through a March 2019 return filed within the extended deadline cannot be denied solely for delay. Limitation-based disallowance, consequential recovery, and related demands are to be removed, with recovered amounts refunded or adjusted against future tax.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4884