RBI supersession powers over multi-State co-operative banks operate independently of the constitutional six-month ceiling and permit statutory extensi...
Charitable sports promotion: sponsorship receipts alone did not defeat registration where funds supported tournaments and player development activitie...
Overdue associated-enterprise receivables: debt-free status defeated notional-interest adjustment, while employee stock-option costs qualified as busi...
Retrospective assessment-limitation amendments validate final orders while contemporaneous segment data governs transfer-pricing comparability and tol...
Page of 4888
Press 'Enter' after typing page number.
1061 to 1080 of 97750 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
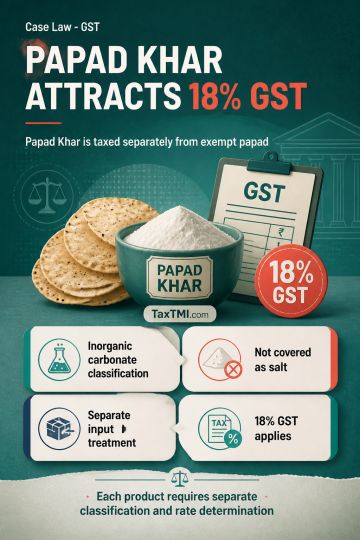
Papad Khar, an alkaline manufactured mixture containing sodium chloride, sodium carbonate and sodium bicarbonate, is classified as an inorganic carbonate under tariff item 28362090. It is not covered by Heading 2501 because it is neither crude nor merely physically processed salt, and it does not possess the characteristics of yeast or prepared baking powder under Heading 2102. As a Chapter 28 inorganic chemical outside the relevant exclusions and alternative schedules, it attracts GST at 18%. Exemption for exempt papad does not extend automatically to Papad Khar used as an input; each input and finished product requires separate classification and rate determination.
Papad Khar, an alkaline manufactured mixture containing sodium chloride, sodium carbonate and sodium bicarbonate, is classified as an inorganic carbonate under tariff item 28362090. It is not covered by Heading 2501 because it is neither crude nor merely physically processed salt, and it does not possess the characteristics of yeast or prepared baking powder under Heading 2102. As a Chapter 28 inorganic chemical outside the relevant exclusions and alternative schedules, it attracts GST at 18%. Exemption for exempt papad does not extend automatically to Papad Khar used as an input; each input and finished product requires separate classification and rate determination.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4888