Prospective customs notification amendments cannot bar provisional release consideration for earlier imports when bills of lading predate their commen...
Personal guarantor insolvency jurisdiction follows the corporate debtor's CIRP Bench, enabling inter-territorial transfer and preventing parallel proc...
Section 47-A undervaluation threshold: fraudulent intent requirement faces reconsideration after referral to a larger Bench for authoritative resoluti...
RBI supersession powers over multi-State co-operative banks operate independently of the constitutional six-month ceiling and permit statutory extensi...
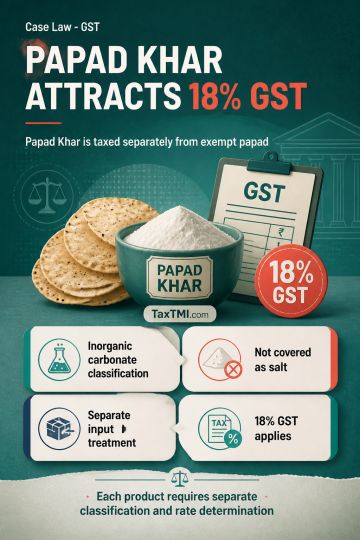
Papad Khar, an alkaline manufactured mixture containing sodium chloride, sodium carbonate and sodium bicarbonate, is classified as an inorganic carbonate under tariff item 28362090. It is not covered by Heading 2501 because it is neither crude nor merely physically processed salt, and it does not possess the characteristics of yeast or prepared baking powder under Heading 2102. As a Chapter 28 inorganic chemical outside the relevant exclusions and alternative schedules, it attracts GST at 18%. Exemption for exempt papad does not extend automatically to Papad Khar used as an input; each input and finished product requires separate classification and rate determination.
Papad Khar, an alkaline manufactured mixture containing sodium chloride, sodium carbonate and sodium bicarbonate, is classified as an inorganic carbonate under tariff item 28362090. It is not covered by Heading 2501 because it is neither crude nor merely physically processed salt, and it does not possess the characteristics of yeast or prepared baking powder under Heading 2102. As a Chapter 28 inorganic chemical outside the relevant exclusions and alternative schedules, it attracts GST at 18%. Exemption for exempt papad does not extend automatically to Papad Khar used as an input; each input and finished product requires separate classification and rate determination.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4884