Credit-note turnover adjustments preserve inverted-duty refunds, while ministerial re-computation does not constitute an impermissible appellate reman...
Revisional jurisdiction over export quota premium deductions requires both error and Revenue prejudice; a permissible assessment view cannot be displa...
Final benami adjudication bars contradictory tax-evasion prosecution where settlement findings confirm full disclosure and cooperation without conceal...
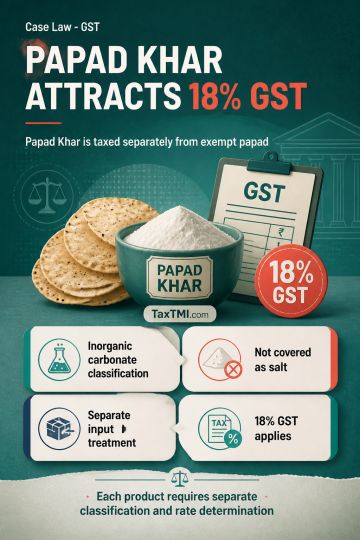
Papad Khar, an alkaline manufactured mixture containing sodium chloride, sodium carbonate and sodium bicarbonate, is classified as an inorganic carbonate under tariff item 28362090. It is not covered by Heading 2501 because it is neither crude nor merely physically processed salt, and it does not possess the characteristics of yeast or prepared baking powder under Heading 2102. As a Chapter 28 inorganic chemical outside the relevant exclusions and alternative schedules, it attracts GST at 18%. Exemption for exempt papad does not extend automatically to Papad Khar used as an input; each input and finished product requires separate classification and rate determination.
Papad Khar, an alkaline manufactured mixture containing sodium chloride, sodium carbonate and sodium bicarbonate, is classified as an inorganic carbonate under tariff item 28362090. It is not covered by Heading 2501 because it is neither crude nor merely physically processed salt, and it does not possess the characteristics of yeast or prepared baking powder under Heading 2102. As a Chapter 28 inorganic chemical outside the relevant exclusions and alternative schedules, it attracts GST at 18%. Exemption for exempt papad does not extend automatically to Papad Khar used as an input; each input and finished product requires separate classification and rate determination.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4883