Charitable trust registration requires a specified-violation notice; settled cash deposits and related-party payments did not justify cancellation or ...
External development charges trigger TDS under section 194C, while disputed administrative payments require factual verification and fresh adjudicatio...
Section 270AA penalty immunity requires identified statutory defaults and a hearing before rejection; reassessment disclosure may constitute under-rep...
Section 80JJAA employee-cost deduction allowed for deployed staff but barred against transfer-pricing income enhancement, with pricing issues remanded...
Page of 4894
Press 'Enter' after typing page number.
1421 to 1440 of 97867 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
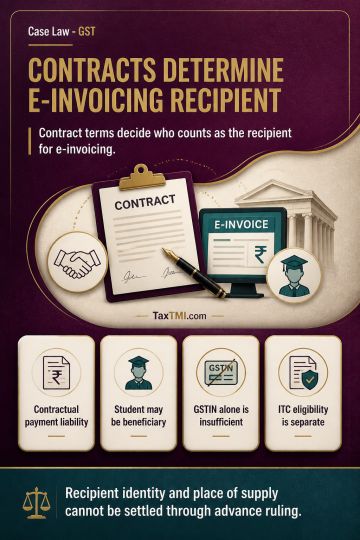
E-invoicing applies to coaching-service supplies genuinely made to registered recipients where the supplier falls within the notified class and no exclusion applies. Recipient status depends on an enforceable contractual liability to pay consideration; the student may be the beneficiary, while a parent, guardian or sponsoring enterprise may be the recipient only if contractual terms establish that liability. Mere fee payment or provision of a GSTIN is insufficient. Proposed-supply questions may be raised, but recipient identity and place of supply cannot be determined through advance ruling where they require transaction-specific assessment. Supplier e-invoicing obligations operate independently of the recipient's input tax credit eligibility or business purpose.
E-invoicing applies to coaching-service supplies genuinely made to registered recipients where the supplier falls within the notified class and no exclusion applies. Recipient status depends on an enforceable contractual liability to pay consideration; the student may be the beneficiary, while a parent, guardian or sponsoring enterprise may be the recipient only if contractual terms establish that liability. Mere fee payment or provision of a GSTIN is insufficient. Proposed-supply questions may be raised, but recipient identity and place of supply cannot be determined through advance ruling where they require transaction-specific assessment. Supplier e-invoicing obligations operate independently of the recipient's input tax credit eligibility or business purpose.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4894