Foundational assessment satisfaction is essential before initiating penalty for cash receipt of immovable-property sale consideration under section 27...
Tax collection at source on purchases removes duplicate withholding obligation, while trade-creditor evidence requires verification before unexplained...
Transfer-pricing comparability requires material turnover effects; adjustments must cover only associated-enterprise transactions and exclude abnormal...
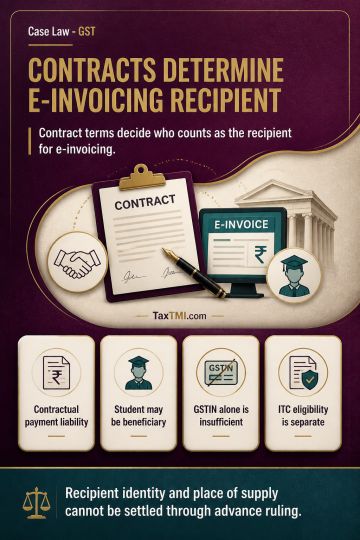
E-invoicing applies to coaching-service supplies genuinely made to registered recipients where the supplier falls within the notified class and no exclusion applies. Recipient status depends on an enforceable contractual liability to pay consideration; the student may be the beneficiary, while a parent, guardian or sponsoring enterprise may be the recipient only if contractual terms establish that liability. Mere fee payment or provision of a GSTIN is insufficient. Proposed-supply questions may be raised, but recipient identity and place of supply cannot be determined through advance ruling where they require transaction-specific assessment. Supplier e-invoicing obligations operate independently of the recipient's input tax credit eligibility or business purpose.
E-invoicing applies to coaching-service supplies genuinely made to registered recipients where the supplier falls within the notified class and no exclusion applies. Recipient status depends on an enforceable contractual liability to pay consideration; the student may be the beneficiary, while a parent, guardian or sponsoring enterprise may be the recipient only if contractual terms establish that liability. Mere fee payment or provision of a GSTIN is insufficient. Proposed-supply questions may be raised, but recipient identity and place of supply cannot be determined through advance ruling where they require transaction-specific assessment. Supplier e-invoicing obligations operate independently of the recipient's input tax credit eligibility or business purpose.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881