Inaccurate-particulars penalties fail where transfer-pricing documentation shows good faith and due diligence, and underlying capital-gains additions ...
Transfer-pricing tolerance for software sub-licensing falls within the services range, eliminating the adjustment and requiring TDS-credit verificatio...
Customs Broker due diligence requires prescribed KYC, not detecting misdeclarations discoverable only through physical examination, defeating licence ...
E-filing system failure permits exclusion of affected time in insolvency appeals, preventing tribunal technology defects from defeating timely filings...
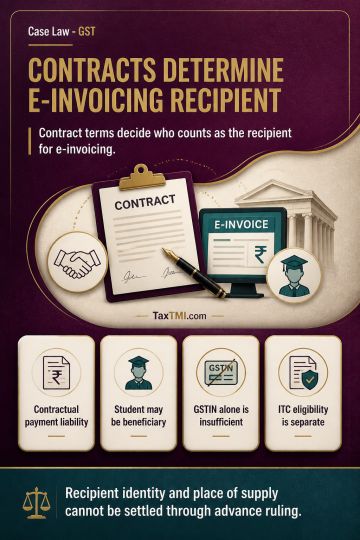
E-invoicing applies to coaching-service supplies genuinely made to registered recipients where the supplier falls within the notified class and no exclusion applies. Recipient status depends on an enforceable contractual liability to pay consideration; the student may be the beneficiary, while a parent, guardian or sponsoring enterprise may be the recipient only if contractual terms establish that liability. Mere fee payment or provision of a GSTIN is insufficient. Proposed-supply questions may be raised, but recipient identity and place of supply cannot be determined through advance ruling where they require transaction-specific assessment. Supplier e-invoicing obligations operate independently of the recipient's input tax credit eligibility or business purpose.
E-invoicing applies to coaching-service supplies genuinely made to registered recipients where the supplier falls within the notified class and no exclusion applies. Recipient status depends on an enforceable contractual liability to pay consideration; the student may be the beneficiary, while a parent, guardian or sponsoring enterprise may be the recipient only if contractual terms establish that liability. Mere fee payment or provision of a GSTIN is insufficient. Proposed-supply questions may be raised, but recipient identity and place of supply cannot be determined through advance ruling where they require transaction-specific assessment. Supplier e-invoicing obligations operate independently of the recipient's input tax credit eligibility or business purpose.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881