Compulsorily convertible debentures remain debt before conversion, preventing transfer-pricing and interest-deduction disallowances on the stated fact...
Stock-in-trade transfer taxability follows possession and consideration, not later conveyance registration, limiting deemed-value provisions to the ac...
Alternative statutory remedy under GST bars writ challenge where classification, notice variance, and hearing disputes require factual appellate revie...
Page of 4896
Press 'Enter' after typing page number.
221 to 240 of 97907 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
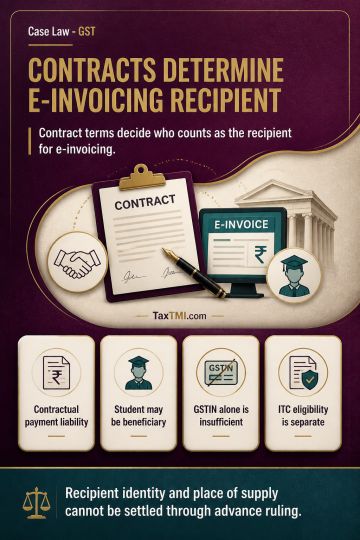
E-invoicing applies to coaching-service supplies genuinely made to registered recipients where the supplier falls within the notified class and no exclusion applies. Recipient status depends on an enforceable contractual liability to pay consideration; the student may be the beneficiary, while a parent, guardian or sponsoring enterprise may be the recipient only if contractual terms establish that liability. Mere fee payment or provision of a GSTIN is insufficient. Proposed-supply questions may be raised, but recipient identity and place of supply cannot be determined through advance ruling where they require transaction-specific assessment. Supplier e-invoicing obligations operate independently of the recipient's input tax credit eligibility or business purpose.
E-invoicing applies to coaching-service supplies genuinely made to registered recipients where the supplier falls within the notified class and no exclusion applies. Recipient status depends on an enforceable contractual liability to pay consideration; the student may be the beneficiary, while a parent, guardian or sponsoring enterprise may be the recipient only if contractual terms establish that liability. Mere fee payment or provision of a GSTIN is insufficient. Proposed-supply questions may be raised, but recipient identity and place of supply cannot be determined through advance ruling where they require transaction-specific assessment. Supplier e-invoicing obligations operate independently of the recipient's input tax credit eligibility or business purpose.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4896