Transfer Pricing Officer jurisdiction is transaction-specific, excluding permanent establishment determinations and requiring independent assessment o...
Rental income valuation requires credible local comparables; family-business salary and commercially expedient unsecured-loan interest remained deduct...
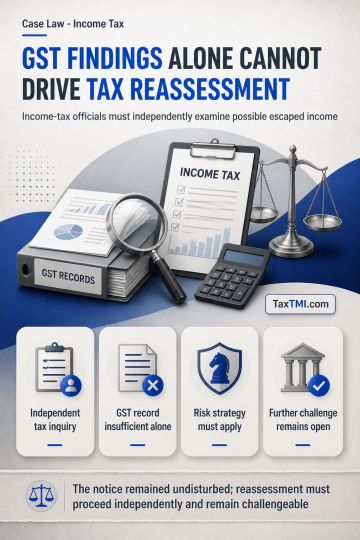
Reassessment based on information linked to GST adjudication requires independent application of the Income-tax Act. Information suggesting escaped income may include material obtained through a CBDT risk-management strategy, but the record must establish that the relevant strategy covers the GST adjudication order. Income-tax authorities cannot rely solely on the GST proceeding or its appellate outcome when issuing or pursuing reassessment. The reassessment notice remained undisturbed, while any reassessment was required to proceed independently under the Income-tax Act and remain open to subsequent challenge.
Reassessment based on information linked to GST adjudication requires independent application of the Income-tax Act. Information suggesting escaped income may include material obtained through a CBDT risk-management strategy, but the record must establish that the relevant strategy covers the GST adjudication order. Income-tax authorities cannot rely solely on the GST proceeding or its appellate outcome when issuing or pursuing reassessment. The reassessment notice remained undisturbed, while any reassessment was required to proceed independently under the Income-tax Act and remain open to subsequent challenge.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881