GST timing for Toll-Operate-Transfer concessions: concessionaires pay integrated tax when operation and maintenance expenses are charged to escrow acc...
Input tax credit conditions for concessional service rates permit limited same-line credits for hotels, catering, and electrically operated vehicle se...
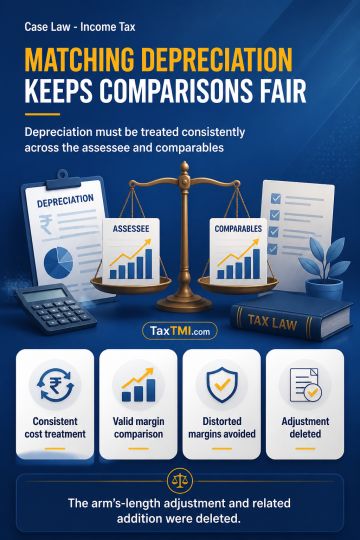
Consistent treatment of depreciation in calculating the profit level indicator under the Transactional Net Margin Method is necessary for a valid arm's-length comparison. Including depreciation in an assessee's operating cost while excluding it from comparable companies' operating costs produces an anomalous comparison and can distort the assessed margin. Recomputing the assessee's margin without depreciation, consistently with the comparables, placed the international transactions with associated enterprises at arm's length. The resulting arm's-length price adjustment and related addition were deleted.
Consistent treatment of depreciation in calculating the profit level indicator under the Transactional Net Margin Method is necessary for a valid arm's-length comparison. Including depreciation in an assessee's operating cost while excluding it from comparable companies' operating costs produces an anomalous comparison and can distort the assessed margin. Recomputing the assessee's margin without depreciation, consistently with the comparables, placed the international transactions with associated enterprises at arm's length. The resulting arm's-length price adjustment and related addition were deleted.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI