Effective hearing in GST adjudication requires actual opportunity to respond; ineffective service through a former auditor invalidated ex parte procee...
Third-party search material requires special assessment route, rendering general reassessment notices without jurisdiction when it forms the proceedin...
Transfer-pricing adjustments must be confined to international associated-enterprise transactions, while functionally dissimilar comparables remain ex...
Insolvency moratorium bars income-tax revision proceedings against corporate debtors until the moratorium ends, preserving merits for later determinat...
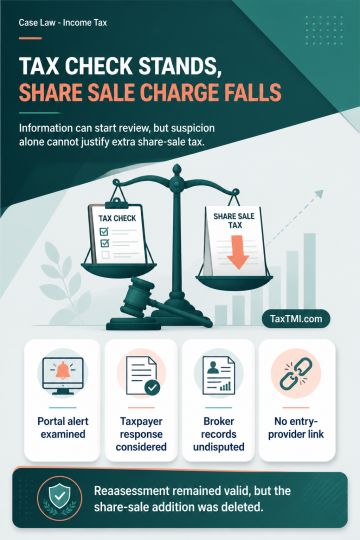
Reassessment initiated on departmental information flagged through the Insight Portal remains valid where the Assessing Officer independently confronts the taxpayer with the information, considers the response, passes an order under section 148A(d), and then issues notice under section 148. Such information may provide a starting point for enquiry without constituting borrowed satisfaction. However, sale proceeds from shares cannot be treated as unexplained accommodation entries merely on investigation allegations or suspicion where broker transactions, demat records, contract notes and banking channels remain undisputed, and no independent corroboration, cash trail, or link to an entry provider is established. The reassessment survived, but the share-sale addition was deleted.
Reassessment initiated on departmental information flagged through the Insight Portal remains valid where the Assessing Officer independently confronts the taxpayer with the information, considers the response, passes an order under section 148A(d), and then issues notice under section 148. Such information may provide a starting point for enquiry without constituting borrowed satisfaction. However, sale proceeds from shares cannot be treated as unexplained accommodation entries merely on investigation allegations or suspicion where broker transactions, demat records, contract notes and banking channels remain undisputed, and no independent corroboration, cash trail, or link to an entry provider is established. The reassessment survived, but the share-sale addition was deleted.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881