Inaccurate-particulars penalties fail where transfer-pricing documentation shows good faith and due diligence, and underlying capital-gains additions ...
Transfer-pricing tolerance for software sub-licensing falls within the services range, eliminating the adjustment and requiring TDS-credit verificatio...
Customs Broker due diligence requires prescribed KYC, not detecting misdeclarations discoverable only through physical examination, defeating licence ...
E-filing system failure permits exclusion of affected time in insolvency appeals, preventing tribunal technology defects from defeating timely filings...
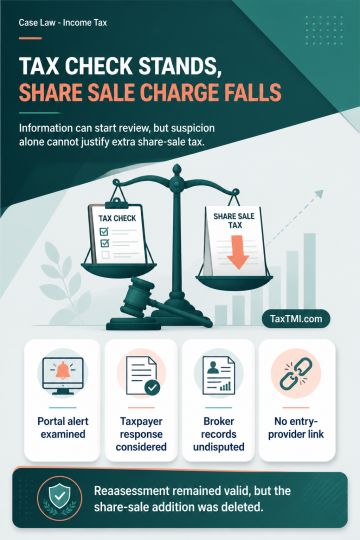
Reassessment initiated on departmental information flagged through the Insight Portal remains valid where the Assessing Officer independently confronts the taxpayer with the information, considers the response, passes an order under section 148A(d), and then issues notice under section 148. Such information may provide a starting point for enquiry without constituting borrowed satisfaction. However, sale proceeds from shares cannot be treated as unexplained accommodation entries merely on investigation allegations or suspicion where broker transactions, demat records, contract notes and banking channels remain undisputed, and no independent corroboration, cash trail, or link to an entry provider is established. The reassessment survived, but the share-sale addition was deleted.
Reassessment initiated on departmental information flagged through the Insight Portal remains valid where the Assessing Officer independently confronts the taxpayer with the information, considers the response, passes an order under section 148A(d), and then issues notice under section 148. Such information may provide a starting point for enquiry without constituting borrowed satisfaction. However, sale proceeds from shares cannot be treated as unexplained accommodation entries merely on investigation allegations or suspicion where broker transactions, demat records, contract notes and banking channels remain undisputed, and no independent corroboration, cash trail, or link to an entry provider is established. The reassessment survived, but the share-sale addition was deleted.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881