Alternative statutory remedy and unexplained delay barred writ review of customs confiscation adjudication, leaving merits for appellate consideration...
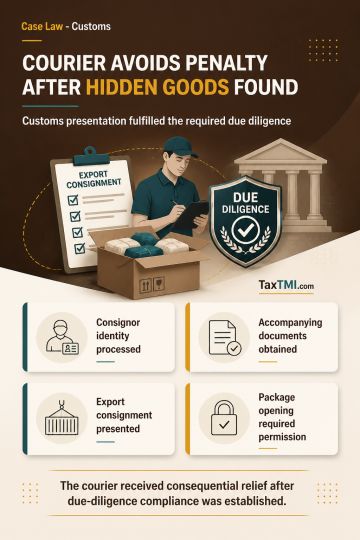
Authorised courier due diligence protects against penalties where declared exports conceal prohibited goods despite proper documentation and customs p...
Customs-controlled container movement now extends to DP World facilities, subject to segregation, inspections, reconciliation, and EXIM cargo priority...
Page of 4893
Press 'Enter' after typing page number.
1381 to 1400 of 97857 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
Section 54F eligibility depends on residential houses owned by the assessee personally. A residential property owned by a company remains the company's asset and is not treated as owned by its director. Where the assessee also jointly owns a property with a spouse, counting that property still leaves only one residential house other than the property in which the qualifying investment is made. The disqualifying condition for ownership of more than one such house therefore does not apply, and the section 54F deduction remains available.
Section 54F eligibility depends on residential houses owned by the assessee personally. A residential property owned by a company remains the company's asset and is not treated as owned by its director. Where the assessee also jointly owns a property with a spouse, counting that property still leaves only one residential house other than the property in which the qualifying investment is made. The disqualifying condition for ownership of more than one such house therefore does not apply, and the section 54F deduction remains available.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4893