Section 153C requires person-specific search authority and year-specific incriminating material for unabated assessments while preventing unsupported ...
Equivalent-value attachment can reach pre-existing assets, but jointly owned property remains protected beyond the accused's attributable proceeds of ...
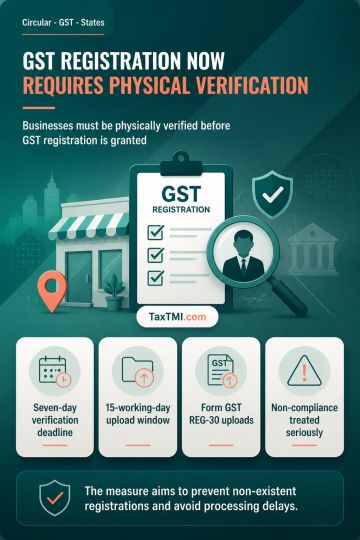
Pre-registration physical verification becomes mandatory to prevent non-existent business registrations and support timely GST registration processing...
Page of 4925
Press 'Enter' after typing page number.
1621 to 1640 of 98494 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
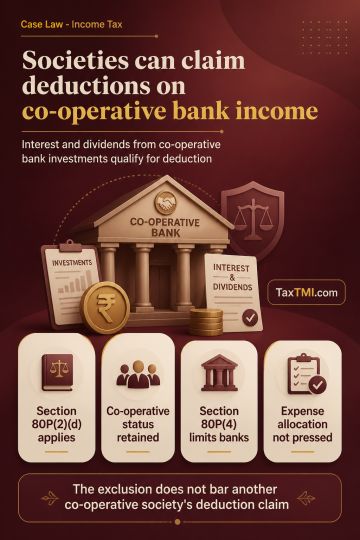
Interest and dividend earned by a co-operative society from deposits or investments with a co-operative bank qualify for deduction under section 80P(2)(d). A co-operative bank registered under co-operative societies law retains its character as a co-operative society for this purpose. Section 80P(4) excludes a co-operative bank from claiming deduction on its own income, but does not bar another co-operative society from claiming deduction on income derived from investments with that bank. The deduction applies to interest and dividends from the co-operative bank; expense-allocation grounds were not pressed.
Interest and dividend earned by a co-operative society from deposits or investments with a co-operative bank qualify for deduction under section 80P(2)(d). A co-operative bank registered under co-operative societies law retains its character as a co-operative society for this purpose. Section 80P(4) excludes a co-operative bank from claiming deduction on its own income, but does not bar another co-operative society from claiming deduction on income derived from investments with that bank. The deduction applies to interest and dividends from the co-operative bank; expense-allocation grounds were not pressed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4925