Capital character of assignment consideration prevents taxation as residuary income, while unsupported interest-related expenditure remains non-deduct...
Make-available condition shields regional support-service receipts from Indian taxation where no independent capability or permanent establishment exi...
Transfer-pricing treatment of corporate guarantees and convertible loans followed prior-year consistency, with taxable foreign dividends excluded from...
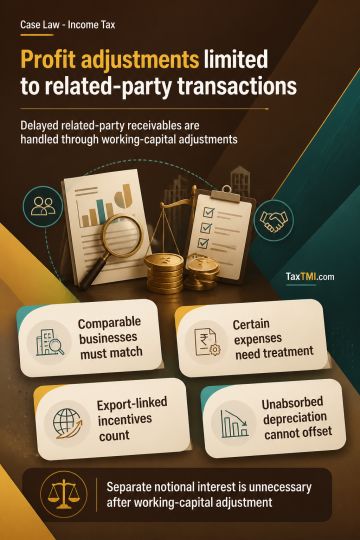
Transfer-pricing benchmarking confines adjustments to associated-enterprise transactions and integrates delayed receivables through TNMM working-capit...
Medical relief status protects government-contracted mobile healthcare from commercial classification, while provisional registration cancellation req...
Charitable registration cancellation requires proof that educational activities abandoned their objects; incidental receipts and retained surplus are ...
Prospective customs notification amendments cannot bar provisional release consideration for earlier imports when bills of lading predate their commen...
Subsisting registration under section 12AB remains legally effective until lawfully withdrawn or cancelled, even if the trust selected an incorrect sub-clause in an earlier registration application. Renewal falls under section 12A(1)(ac)(ii) where an existing section 12AB registration is due to expire. Absence of registration under the earlier section 12A/12AA regime does not justify rejection where no adverse finding concerns the objects, genuineness of activities, or registration conditions. Renewal rejection on that basis was set aside and registration was directed for the applicable period.
Subsisting registration under section 12AB remains legally effective until lawfully withdrawn or cancelled, even if the trust selected an incorrect sub-clause in an earlier registration application. Renewal falls under section 12A(1)(ac)(ii) where an existing section 12AB registration is due to expire. Absence of registration under the earlier section 12A/12AA regime does not justify rejection where no adverse finding concerns the objects, genuineness of activities, or registration conditions. Renewal rejection on that basis was set aside and registration was directed for the applicable period.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881