E-filing system failure permits exclusion of affected time in insolvency appeals, preventing tribunal technology defects from defeating timely filings...
Pre-existing disputes over outcome-based professional fees can bar Section 9 insolvency proceedings where contractual entitlement requires investigati...
Corresponding scheduled offences preserve money-laundering jurisdiction despite repeal of the central corruption provision where conduct remains cover...
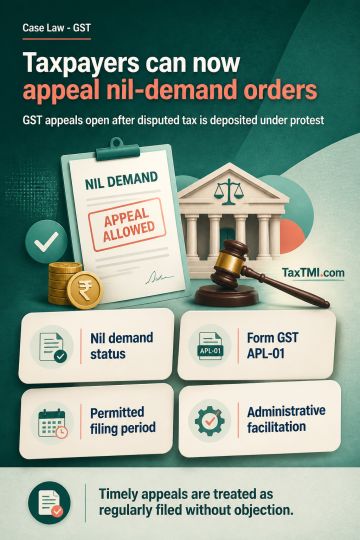
GST portal access now permits statutory appeals in Form GST APL-01 against nil demand orders where the disputed demand was deposited under protest. An appeal filed within the permitted period through this enabled facility is to be treated as regularly filed without objection. The portal change addresses access-to-justice barriers created when a nil demand status previously prevented appeal filing. Administrative instructions were to be considered to facilitate the same process for similarly situated taxpayers.
GST portal access now permits statutory appeals in Form GST APL-01 against nil demand orders where the disputed demand was deposited under protest. An appeal filed within the permitted period through this enabled facility is to be treated as regularly filed without objection. The portal change addresses access-to-justice barriers created when a nil demand status previously prevented appeal filing. Administrative instructions were to be considered to facilitate the same process for similarly situated taxpayers.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4884