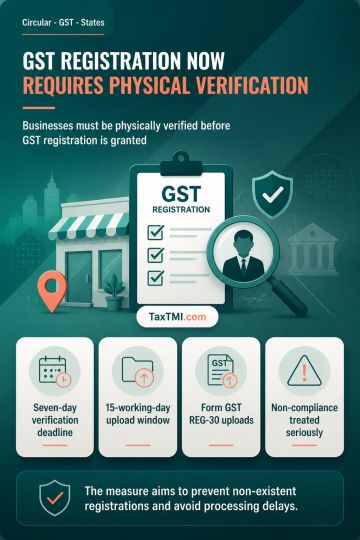
Pre-registration physical verification becomes mandatory to prevent non-existent business registrations and support timely GST registration processing...
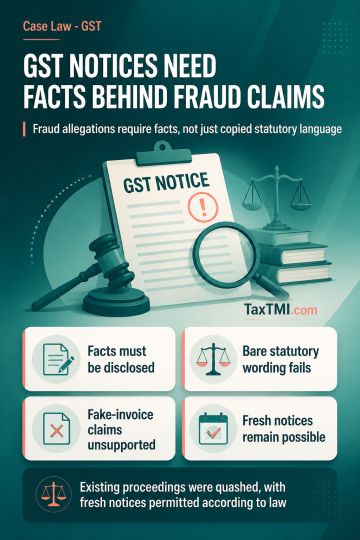
GST notices alleging fraud, wilful misrepresentation or suppression must disclose the foundational facts supporting those allegations. Mere reproduction of statutory expressions, without reasons showing application of mind, does not sustain proceedings alleging input tax credit availed through fake invoices without actual supply of goods. Notices lacking sufficient reasons were quashed, while preserving the authority's liberty to issue fresh notices in accordance with law.
GST notices alleging fraud, wilful misrepresentation or suppression must disclose the foundational facts supporting those allegations. Mere reproduction of statutory expressions, without reasons showing application of mind, does not sustain proceedings alleging input tax credit availed through fake invoices without actual supply of goods. Notices lacking sufficient reasons were quashed, while preserving the authority's liberty to issue fresh notices in accordance with law.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881