Commodity derivatives position limits adopt revised breach penalties, broad commodity criteria, and client open-position limits based on deliverable s...
Effective hearing in GST adjudication requires actual opportunity to respond; ineffective service through a former auditor invalidated ex parte procee...
Third-party search material requires special assessment route, rendering general reassessment notices without jurisdiction when it forms the proceedin...
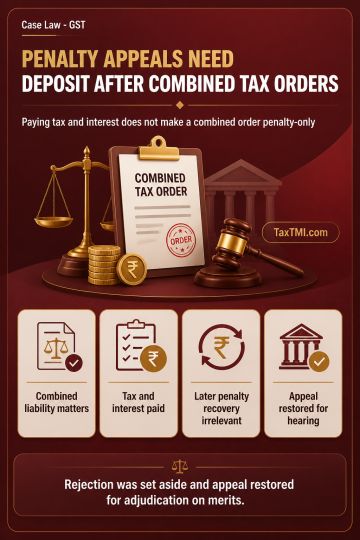
Statutory pre-deposit for an appeal against a penalty order does not apply under the proviso where the original order imposed a composite liability for tax, interest and penalty. Payment of the tax and interest components does not convert that original composite order into an order demanding penalty alone. A later recovery order confined to penalty likewise does not alter the character of the original order. Accordingly, rejection of the appeal for failure to deposit ten per cent of the penalty was set aside and the appeal was restored for adjudication on merits.
Statutory pre-deposit for an appeal against a penalty order does not apply under the proviso where the original order imposed a composite liability for tax, interest and penalty. Payment of the tax and interest components does not convert that original composite order into an order demanding penalty alone. A later recovery order confined to penalty likewise does not alter the character of the original order. Accordingly, rejection of the appeal for failure to deposit ten per cent of the penalty was set aside and the appeal was restored for adjudication on merits.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4894