Capital-gains exemption for charitable trusts extends to qualifying fixed deposits, while unrecoverable TDS write-offs may constitute income applicati...
India-UK treaty characterisation of telecom-service receipts as business profits withstands unilateral domestic-law amendments for Indian tax purposes...
Transfer-pricing reimbursement adjustments require uncontrolled comparables and cannot become expense-genuineness reviews, resulting in deletion of th...
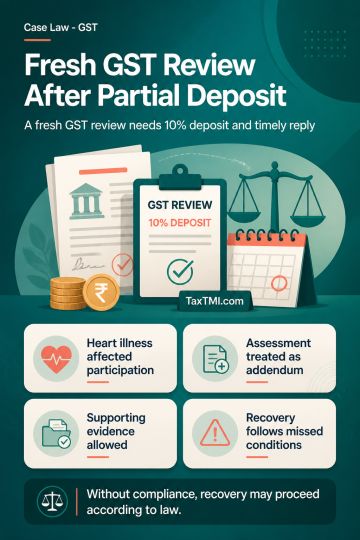
Conditional de novo GST adjudication may be granted where an assessee shows inability to participate because of heart illness and undertakes to make a partial pre-deposit. The assessment may be quashed and treated as an addendum to the show-cause notice, allowing a fresh reply with supporting documents. Fresh adjudication is conditional on cash deposit of 10% of disputed tax and timely submission of the reply; failing compliance, recovery may proceed according to law.
Conditional de novo GST adjudication may be granted where an assessee shows inability to participate because of heart illness and undertakes to make a partial pre-deposit. The assessment may be quashed and treated as an addendum to the show-cause notice, allowing a fresh reply with supporting documents. Fresh adjudication is conditional on cash deposit of 10% of disputed tax and timely submission of the reply; failing compliance, recovery may proceed according to law.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4888