Customs-controlled cargo movement now includes GDL, subject to EXIM prioritisation, segregation, verification, reconciliation and enforcement safeguar...
GST cross-empowerment remains effective without conditional notification, while duplicate proceedings require established safeguards against overlappi...
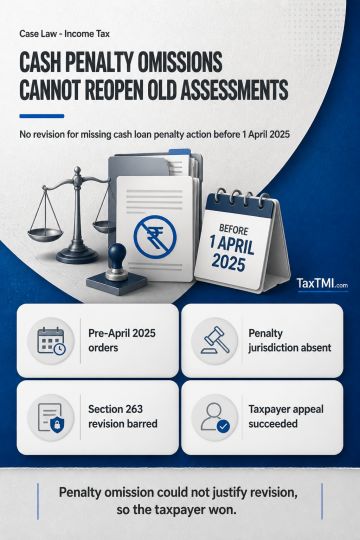
For assessment orders passed before 1 April 2025, the Assessing Officer lacked jurisdiction to impose or initiate penalty proceedings for contravention of cash loan or deposit restrictions under section 271D. Non-initiation of such penalty proceedings therefore could not make the assessment order erroneous and prejudicial to the interests of the Revenue for revision under section 263. A revisionary order founded solely on that omission was set aside, and the taxpayer's appeal was allowed.
For assessment orders passed before 1 April 2025, the Assessing Officer lacked jurisdiction to impose or initiate penalty proceedings for contravention of cash loan or deposit restrictions under section 271D. Non-initiation of such penalty proceedings therefore could not make the assessment order erroneous and prejudicial to the interests of the Revenue for revision under section 263. A revisionary order founded solely on that omission was set aside, and the taxpayer's appeal was allowed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4894