Restricted gold import conditions: breach permits absolute confiscation, while redemption remains discretionary and is rarely disturbed on writ review...
Bail conditions in customs-duty evasion investigation permit continued inquiry while addressing evidence-tampering concerns through procedural safegua...
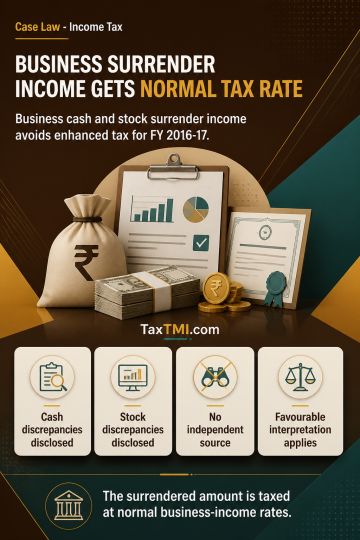
Surrendered income arising from cash and stock discrepancies at business premises, and disclosed in the profit and loss account, is treated as business income where no independent undisclosed asset or non-business source is identified. The enhanced tax rate under section 115BBE, effective from 1 April 2017 without express retrospective operation, does not apply to FY 2016-17. Where competing reasonable interpretations of an ambiguous taxing provision are available and no jurisdictional High Court ruling governs, the interpretation favourable to the assessee applies. The surrendered income is consequently taxable at the normal business-income rate.
Surrendered income arising from cash and stock discrepancies at business premises, and disclosed in the profit and loss account, is treated as business income where no independent undisclosed asset or non-business source is identified. The enhanced tax rate under section 115BBE, effective from 1 April 2017 without express retrospective operation, does not apply to FY 2016-17. Where competing reasonable interpretations of an ambiguous taxing provision are available and no jurisdictional High Court ruling governs, the interpretation favourable to the assessee applies. The surrendered income is consequently taxable at the normal business-income rate.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4891