Withdrawal of obsolete FEMA circulars streamlines rules on external commercial borrowings, non-resident bond investments, and money transfer sub-agent...
Departmental appeal limitation after call-book recall preserves original filing, while documented correlation supports SAD refund on imported granules...
Income-tax prosecution fails when appellate remand removes its factual foundation; directors require company arraignment for vicarious criminal liabil...
Page of 4881
Press 'Enter' after typing page number.
881 to 900 of 97618 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
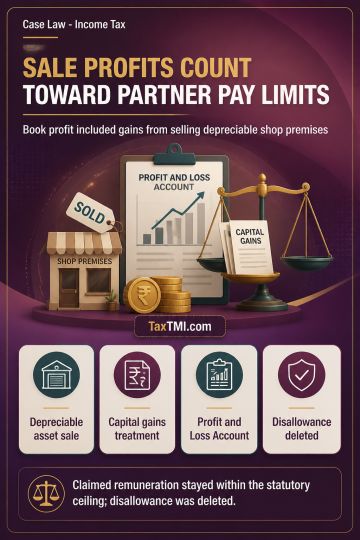
Section 50's deeming fiction treats gains on transfer of depreciable assets as short-term capital gains only for capital-gains computation. It does not exclude commercial profit credited to the Profit and Loss Account from book profit used to determine the ceiling on working partners' remuneration. Explanation 3 to section 40(b) starts with net profit in the Profit and Loss Account, subject to Chapter IV-D adjustments and add-back of remuneration already deducted, rather than excluding receipts taxable under another income head. Profit from sale of depreciable shop premises therefore remained in book profit, making the claimed partners' remuneration within the statutory ceiling and requiring deletion of the disallowance.
Section 50's deeming fiction treats gains on transfer of depreciable assets as short-term capital gains only for capital-gains computation. It does not exclude commercial profit credited to the Profit and Loss Account from book profit used to determine the ceiling on working partners' remuneration. Explanation 3 to section 40(b) starts with net profit in the Profit and Loss Account, subject to Chapter IV-D adjustments and add-back of remuneration already deducted, rather than excluding receipts taxable under another income head. Profit from sale of depreciable shop premises therefore remained in book profit, making the claimed partners' remuneration within the statutory ceiling and requiring deletion of the disallowance.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881