Transfer Pricing Officer jurisdiction is transaction-specific, excluding permanent establishment determinations and requiring independent assessment o...
Rental income valuation requires credible local comparables; family-business salary and commercially expedient unsecured-loan interest remained deduct...
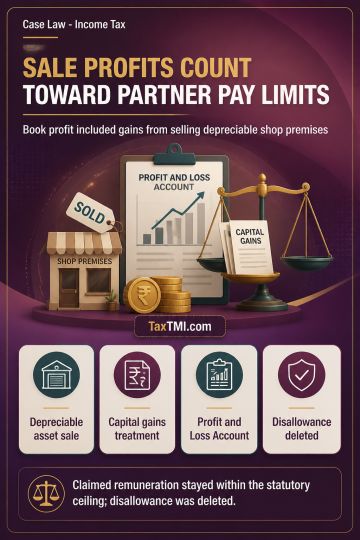
Section 50's deeming fiction treats gains on transfer of depreciable assets as short-term capital gains only for capital-gains computation. It does not exclude commercial profit credited to the Profit and Loss Account from book profit used to determine the ceiling on working partners' remuneration. Explanation 3 to section 40(b) starts with net profit in the Profit and Loss Account, subject to Chapter IV-D adjustments and add-back of remuneration already deducted, rather than excluding receipts taxable under another income head. Profit from sale of depreciable shop premises therefore remained in book profit, making the claimed partners' remuneration within the statutory ceiling and requiring deletion of the disallowance.
Section 50's deeming fiction treats gains on transfer of depreciable assets as short-term capital gains only for capital-gains computation. It does not exclude commercial profit credited to the Profit and Loss Account from book profit used to determine the ceiling on working partners' remuneration. Explanation 3 to section 40(b) starts with net profit in the Profit and Loss Account, subject to Chapter IV-D adjustments and add-back of remuneration already deducted, rather than excluding receipts taxable under another income head. Profit from sale of depreciable shop premises therefore remained in book profit, making the claimed partners' remuneration within the statutory ceiling and requiring deletion of the disallowance.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881