Pure-service exemption for municipal sanitation manpower requires an identifiable qualifying municipal-function supply, leaving non-exempt outsourcing...
Higher depreciation for mining dumpers applies when composite contracts require transportation services, rather than merely incidental internal vehicl...
Knowledge requirement for customs penalties: unverified retracted statements could not establish cigarette-related liability, while goods were release...
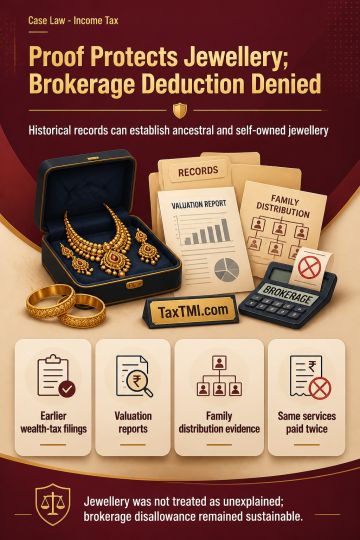
Historical wealth-tax records, valuation reports and family-distribution evidence can substantiate ancestral and self-owned jewellery; non-filing of later wealth-tax returns, without evidence of disposal, does not establish that prior holdings were sold. Accordingly, jewellery disclosed in Schedule AL could not be treated as unexplained merely because original purchase bills were unavailable. Brokerage paid to a Hindu undivided family is not deductible as investment cost for capital-gains exemption where no family fund or asset generated the income and its Karta or coparcener was separately paid for the same personal services. Recipient confirmation or taxability does not establish deductibility; the brokerage disallowance remained sustainable.
Historical wealth-tax records, valuation reports and family-distribution evidence can substantiate ancestral and self-owned jewellery; non-filing of later wealth-tax returns, without evidence of disposal, does not establish that prior holdings were sold. Accordingly, jewellery disclosed in Schedule AL could not be treated as unexplained merely because original purchase bills were unavailable. Brokerage paid to a Hindu undivided family is not deductible as investment cost for capital-gains exemption where no family fund or asset generated the income and its Karta or coparcener was separately paid for the same personal services. Recipient confirmation or taxability does not establish deductibility; the brokerage disallowance remained sustainable.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4937