Loading...

⚠ ✕
❮ Top
☎ Help
☰
×

By creating an account you can:

Logo TaxTMI
Call Us / Help / Feedback✕

Contact Us At :

✉ E-mail: [email protected]

✆ Call / WhatsApp at: +91 99117 96707

For more information, Check Contact Us

FAQs :

To know Frequently Asked Questions, Check FAQs

Most Asked Video Tutorials :

For more tutorials, Check Video Tutorials

Submit Feedback/Suggestion :

Email :
Please provide your email address so we can follow up on your feedback.
Category :
Description :
Min 15 characters 0/2000
Make Most of Text Search ✕
  1. Checkout this video tutorial: How to search effectively on TaxTMI.
  2. Put words in double quotes for exact word search, eg: "income tax"
  3. Avoid noise words such as : 'and, of, the, a'
  4. Sort by Relevance to get the most relevant document.
  5. Press Enter to add multiple terms/multiple phrases, and then click on Search to Search.
  6. Text Search
  7. The system will try to fetch results that contains ALL your words.
  8. Once you add keywords, you'll see a new 'Search In' filter that makes your results even more precise.
  9. Text Search
╳
Add to...
You have not created any category. Kindly create one to bookmark this item!
✕
Create New Category
Hide
Title :
Description :
❮❮ Hide
❮ Default View
Expand ❯❯
Close ✕
🔎 Filters / Advanced Search ❯
TEXT

Press 'Enter' to add multiple search terms. Rules for Better Search

Search In
Main Text + AI Text ❯
  • Main Text
  • Main Text + AI Text
  • AI Text
Law:
---- All Laws---- ❯
  • ---- All Laws----
  • Income Tax
  • Direct Taxes
  • Benami Property
  • Central GST Laws
  • SGST - State GST Laws
  • Customs
  • FTP - Foreign Trade Policy
  • SEZ - Special Economic Zone
  • FEMA - Foreign Exchange Management
  • Companies Law
  • SEBI - Securities & Exchange Board of India
  • IBC - Insolvency and Bankruptcy
  • Law of Competition
  • PMLA - Money-Laundering
  • Indian Laws
  • Bill / Finance Bills
  • Wealth Tax
  • Service Tax
  • Central Excise
  • VAT / Sales Tax
Month:
---- All Months ---- ❯
  • ---- All Months ----
  • January
  • February
  • March
  • April
  • May
  • June
  • July
  • August
  • September
  • October
  • November
  • December
Year:
---- All Years ---- ❯
  • ---- All Years ----
  • 2026
  • 2025
  • 2024
  • 2023
  • 2022
  • 2021
  • 2020
  • 2019
  • 2018
  • 2017
  • 2016
  • 2015
  • 2014
  • 2013
  • 2012
  • 2011
Sort By: ?
In Sort By 'Default', exact matches for text search are shown at the top, followed by the remaining results in their regular order.
Relevance Default Date
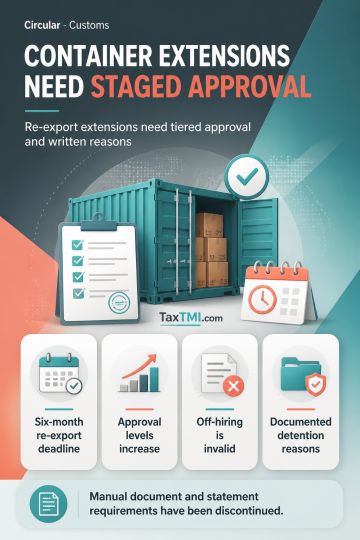
    Container re-export extensions follow a tiered approval process; off-hiring is invalid, while detention-related requests require documented reasons.
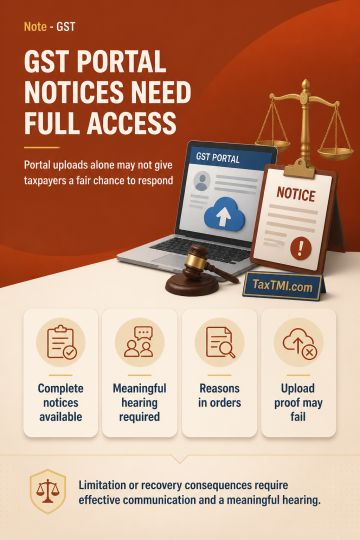
    Common Portal Service requires accessible full GST communications and meaningful hearing before limitation or recovery consequences follow.
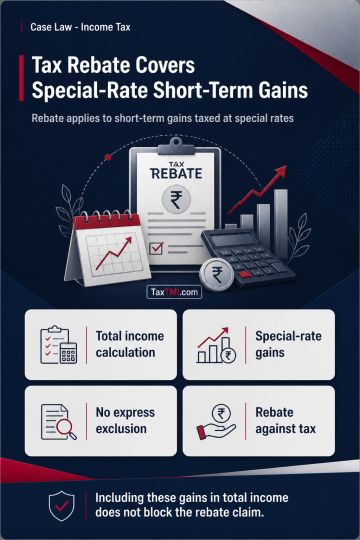
    Tax rebate on total income extends to short-term capital gains taxed at special rates without express exclusion.
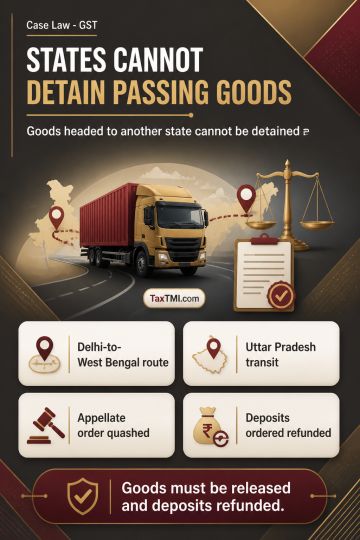
    Inter-State transit goods cannot be detained by GST authorities of a State merely because they pass through its territory.
    Alternative GST remedies limit writ review where registration-cancellation disputes require factual examination by appellate authorities.
    Retrospective input tax credit limitation extension protects eligible belated claims and requires reversal of time-barred credit disallowance.
    Defective GST portal service justified condonation of delay, requiring the appellate authority to hear the appeal on merits.
    Sufficient cause for delayed GST appeals permits merits review where portal placement prevented effective notice.
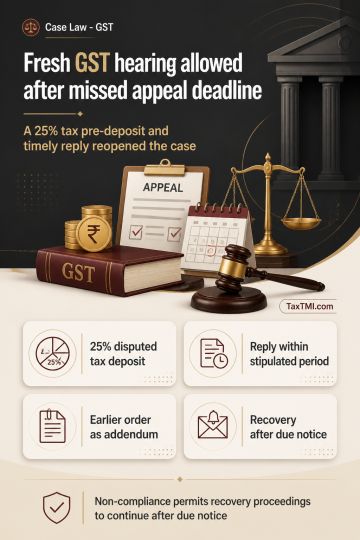
    Conditional pre-deposit enables fresh adjudication after non-participation and expiry of appellate limitation, subject to a timely reply.
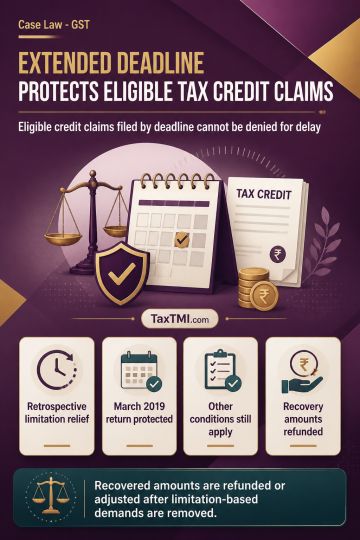
    Retrospective input tax credit limitation extension preserves eligible claims filed within the extended return-filing deadline.
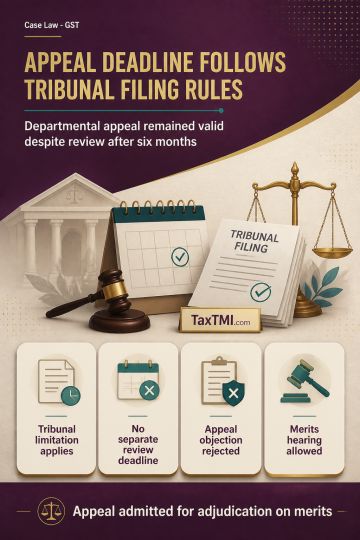
    Tribunal appeal limitation governs filing deadlines, not the Commissioner's review period, preserving departmental appeal maintainability.
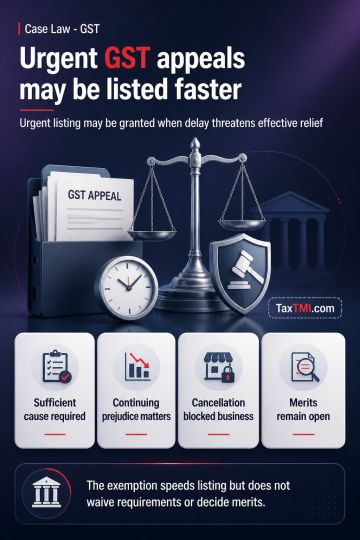
    Urgent listing for GST registration cancellation appeals may bypass Registry scrutiny where delay threatens effective appellate relief.
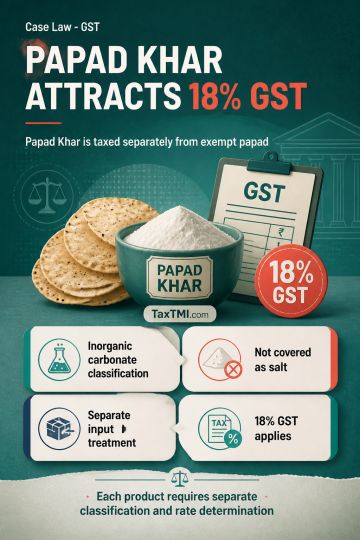
    Tariff classification of Papad Khar as an inorganic carbonate results in GST despite exempt papad production.
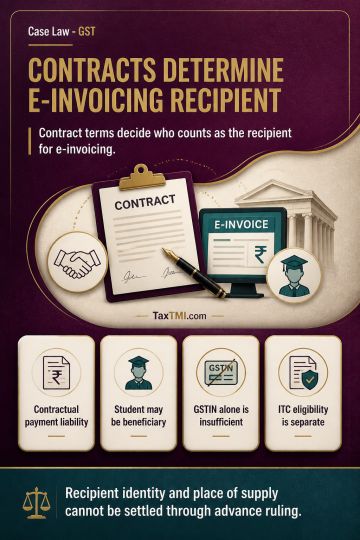
    E-invoicing for coaching services depends on contractual recipient status, not merely fee payment, GSTIN disclosure, or input tax credit eligibility.
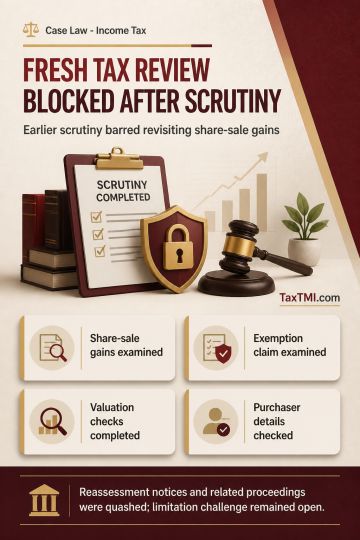
    Change of opinion bars reassessment where scrutiny already examined share-sale gains and the related capital-gains exemption claim.
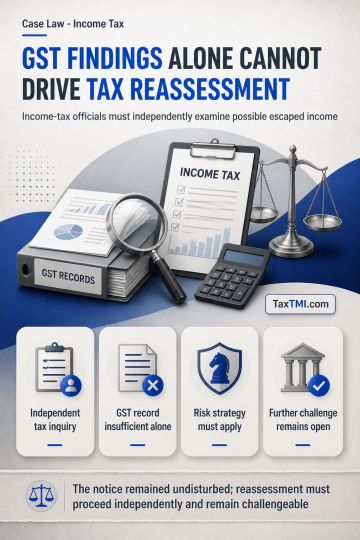
    Reassessment Based on GST Adjudication Requires Independent Income-Tax Inquiry Rather Than Sole Reliance on GST Proceedings
    Consistent depreciation treatment under TNMM prevents distorted margins and removes arm's-length adjustments for associated-enterprise transactions.
    Section 87A rebate covers tax on short-term capital gains under special rates when total income remains within the threshold.
    Reassessment based on departmental intelligence survives independent review, but suspicion alone cannot sustain unexplained share-sale additions.
    Uncorroborated electronic records cannot alone support tax additions, while unproved cash rent and stock discrepancies remain disallowed.
❮
❯
❯❯
Maximize Maximize Maximize
0 / 200
Expand Note
Add to Folder

No Folders have been created

+

Are you sure you want to delete "My most important" ?

NOTE:

Highlights
Showing Results for :
Reset Filters
Results Found:
Show All Summaries Hide All Summaries

Highlights

Back

All Highlights

Showing Results for :
Reset Filters
No Records Found

Highlights

Back

All Highlights

Charitable entities whose exemption under sections 11 and 12 is...

Charitable donations qualify as deductions from income from other sources when made to advance the entity's objects.

Contents
Summary
Note

Note

-

Bookmark

Print

Print

Income Tax September 14, 2026 Case Laws AT
Charitable entities whose exemption under sections 11 and 12 is not claimed may deduct expenditure incurred to advance their charitable objects when income is assessed under "Income from Other Sources". Section 57(iii) applies to the computation of such income, including donations made in furtherance of those objects. Applying the coordinate-bench approach where no material factual or legal distinction existed, ITAT deleted the disallowance of the donations and allowed the deduction. The alternative deduction claim under section 80G required no separate adjudication.

Topics

Acts Income Tax