GST payment representations require record-based, reasoned decisions while substantive entitlement remains open for determination by competent authori...
Reassessment sanction under extended limitation required approval from the competent specified authority, invalidating proceedings approved by an inco...
Internal CUP benchmarking for fixed-rate Masala Bonds prevails over floating external comparables, eliminating the related transfer-pricing adjustment...
Page of 4881
Press 'Enter' after typing page number.
981 to 1000 of 97618 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
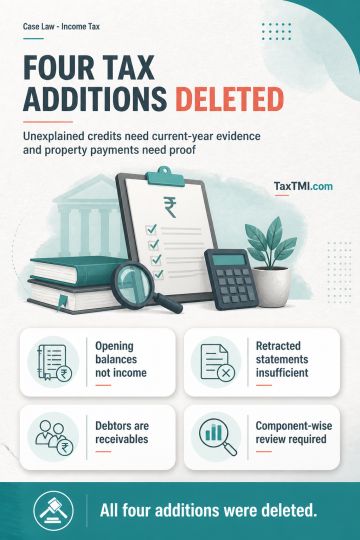
Brought-forward capital cannot be assessed as current-year income merely because an originally reported balance-sheet figure is erroneous; a demonstrable accounting correction supported by accepted prior-year records is permissible absent evidence of fresh unexplained accretion. Alleged on-money for immovable property requires cogent proof of actual payment, and a retracted vendor statement or unconnected cash deposits does not establish ownership of unexplained money. Section 68 requires a credit arising in the relevant year, so aggregate closing creditor balances, internal appropriations, prior-year liabilities and supported chit liabilities cannot be taxed without component-wise examination. Recorded sundry debtors are debit receivables, not cash credits or unrecorded investments. On these principles, the four additions were deleted.
Brought-forward capital cannot be assessed as current-year income merely because an originally reported balance-sheet figure is erroneous; a demonstrable accounting correction supported by accepted prior-year records is permissible absent evidence of fresh unexplained accretion. Alleged on-money for immovable property requires cogent proof of actual payment, and a retracted vendor statement or unconnected cash deposits does not establish ownership of unexplained money. Section 68 requires a credit arising in the relevant year, so aggregate closing creditor balances, internal appropriations, prior-year liabilities and supported chit liabilities cannot be taxed without component-wise examination. Recorded sundry debtors are debit receivables, not cash credits or unrecorded investments. On these principles, the four additions were deleted.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881