Charitable sports promotion: sponsorship receipts alone did not defeat registration where funds supported tournaments and player development activitie...
Overdue associated-enterprise receivables: debt-free status defeated notional-interest adjustment, while employee stock-option costs qualified as busi...
Retrospective assessment-limitation amendments validate final orders while contemporaneous segment data governs transfer-pricing comparability and tol...
Transfer pricing adjustments must track international transactions, while unsupported AMP adjustments and unsuitable manufacturing comparables require...
Transfer-pricing adjustments must reflect functional comparability, working-capital effects, and avoid duplicating interest on associated-enterprise r...
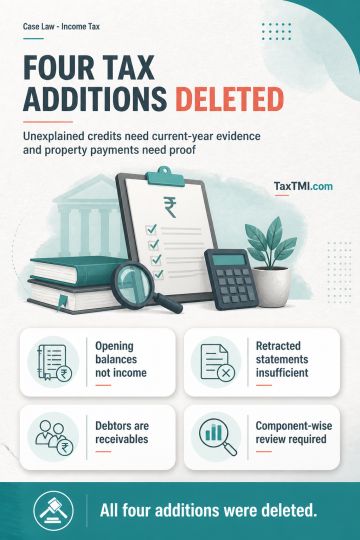
Brought-forward capital cannot be assessed as current-year income merely because an originally reported balance-sheet figure is erroneous; a demonstrable accounting correction supported by accepted prior-year records is permissible absent evidence of fresh unexplained accretion. Alleged on-money for immovable property requires cogent proof of actual payment, and a retracted vendor statement or unconnected cash deposits does not establish ownership of unexplained money. Section 68 requires a credit arising in the relevant year, so aggregate closing creditor balances, internal appropriations, prior-year liabilities and supported chit liabilities cannot be taxed without component-wise examination. Recorded sundry debtors are debit receivables, not cash credits or unrecorded investments. On these principles, the four additions were deleted.
Brought-forward capital cannot be assessed as current-year income merely because an originally reported balance-sheet figure is erroneous; a demonstrable accounting correction supported by accepted prior-year records is permissible absent evidence of fresh unexplained accretion. Alleged on-money for immovable property requires cogent proof of actual payment, and a retracted vendor statement or unconnected cash deposits does not establish ownership of unexplained money. Section 68 requires a credit arising in the relevant year, so aggregate closing creditor balances, internal appropriations, prior-year liabilities and supported chit liabilities cannot be taxed without component-wise examination. Recorded sundry debtors are debit receivables, not cash credits or unrecorded investments. On these principles, the four additions were deleted.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881