Withdrawal of obsolete FEMA circulars streamlines rules on external commercial borrowings, non-resident bond investments, and money transfer sub-agent...
Departmental appeal limitation after call-book recall preserves original filing, while documented correlation supports SAD refund on imported granules...
Income-tax prosecution fails when appellate remand removes its factual foundation; directors require company arraignment for vicarious criminal liabil...
Page of 4881
Press 'Enter' after typing page number.
881 to 900 of 97618 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
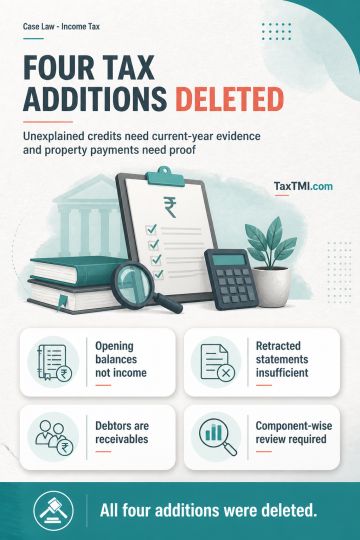
Brought-forward capital cannot be assessed as current-year income merely because an originally reported balance-sheet figure is erroneous; a demonstrable accounting correction supported by accepted prior-year records is permissible absent evidence of fresh unexplained accretion. Alleged on-money for immovable property requires cogent proof of actual payment, and a retracted vendor statement or unconnected cash deposits does not establish ownership of unexplained money. Section 68 requires a credit arising in the relevant year, so aggregate closing creditor balances, internal appropriations, prior-year liabilities and supported chit liabilities cannot be taxed without component-wise examination. Recorded sundry debtors are debit receivables, not cash credits or unrecorded investments. On these principles, the four additions were deleted.
Brought-forward capital cannot be assessed as current-year income merely because an originally reported balance-sheet figure is erroneous; a demonstrable accounting correction supported by accepted prior-year records is permissible absent evidence of fresh unexplained accretion. Alleged on-money for immovable property requires cogent proof of actual payment, and a retracted vendor statement or unconnected cash deposits does not establish ownership of unexplained money. Section 68 requires a credit arising in the relevant year, so aggregate closing creditor balances, internal appropriations, prior-year liabilities and supported chit liabilities cannot be taxed without component-wise examination. Recorded sundry debtors are debit receivables, not cash credits or unrecorded investments. On these principles, the four additions were deleted.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881