Strict construction of customs exemptions denied concession for brake components, while limitation restricted differential duty to timely Bills of Ent...
Way Leave Permissions cannot be retrospectively revived through insolvency plans, and affected infrastructure holders require safety review and hearin...
Inter-terminal container movement requires customs escort, permit reconciliation, and indemnity, while delayed DPD cargo may move to designated CFS ya...
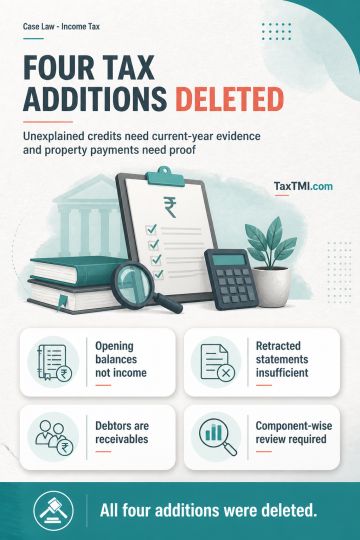
Brought-forward capital cannot be assessed as current-year income merely because an originally reported balance-sheet figure is erroneous; a demonstrable accounting correction supported by accepted prior-year records is permissible absent evidence of fresh unexplained accretion. Alleged on-money for immovable property requires cogent proof of actual payment, and a retracted vendor statement or unconnected cash deposits does not establish ownership of unexplained money. Section 68 requires a credit arising in the relevant year, so aggregate closing creditor balances, internal appropriations, prior-year liabilities and supported chit liabilities cannot be taxed without component-wise examination. Recorded sundry debtors are debit receivables, not cash credits or unrecorded investments. On these principles, the four additions were deleted.
Brought-forward capital cannot be assessed as current-year income merely because an originally reported balance-sheet figure is erroneous; a demonstrable accounting correction supported by accepted prior-year records is permissible absent evidence of fresh unexplained accretion. Alleged on-money for immovable property requires cogent proof of actual payment, and a retracted vendor statement or unconnected cash deposits does not establish ownership of unexplained money. Section 68 requires a credit arising in the relevant year, so aggregate closing creditor balances, internal appropriations, prior-year liabilities and supported chit liabilities cannot be taxed without component-wise examination. Recorded sundry debtors are debit receivables, not cash credits or unrecorded investments. On these principles, the four additions were deleted.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881