Business expenditure and depreciation rules allow operational outgoings while limiting disallowances for personal elements and unsupported third-party...
Compromise-and-arrangement extensions may accommodate debt assignment where creditor commercial judgment supports value maximisation and avoids proced...
Delayed-payment surcharge is not taxable tolerance consideration where it penalises default, while meter testing follows electricity distribution trea...
Sufficient cause for delayed revenue income-tax appeals requires bona fides, due diligence and a credible explanation; otherwise limitation bars appea...
Inverted-duty-structure refunds remain available for unchanged-rate apparel supplies despite trader status and require tax-period-specific computation...
Page of 4881
Press 'Enter' after typing page number.
781 to 800 of 97618 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
Business-expenditure and depreciation principles support...
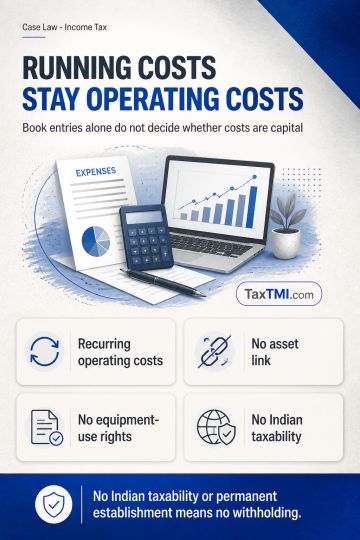
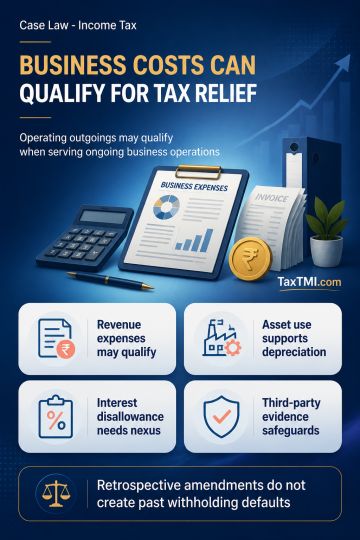
Business expenditure and depreciation rules allow operational outgoings while limiting disallowances for personal elements and unsupported third-party allegations.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
Business-expenditure and depreciation principles support deduction where expenditure serves ongoing operations without creating a capital asset or ownership right. Public-road contributions, compensatory afforestation, dry docking, mining-lease renewal stamp duty, dumping conversion charges, obsolete inventory write-offs and irrecoverable supplier advances are treated as revenue or business outgoings on the stated conditions. Depreciation is linked to use of any asset within a block and may extend to qualifying commercial vehicles, energy-saving generators and brought-forward goodwill. Interest disallowance is not justified where interest-free funds exceed investments or no borrowing-advance nexus exists. Withholding is not triggered for export-price adjustments or non-resident payments not chargeable when paid; retrospective amendments do not create past defaults. Cross-examination safeguards apply to third-party material.
Business-expenditure and depreciation principles support deduction where expenditure serves ongoing operations without creating a capital asset or ownership right. Public-road contributions, compensatory afforestation, dry docking, mining-lease renewal stamp duty, dumping conversion charges, obsolete inventory write-offs and irrecoverable supplier advances are treated as revenue or business outgoings on the stated conditions. Depreciation is linked to use of any asset within a block and may extend to qualifying commercial vehicles, energy-saving generators and brought-forward goodwill. Interest disallowance is not justified where interest-free funds exceed investments or no borrowing-advance nexus exists. Withholding is not triggered for export-price adjustments or non-resident payments not chargeable when paid; retrospective amendments do not create past defaults. Cross-examination safeguards apply to third-party material.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881