Strict construction of customs exemptions denied concession for brake components, while limitation restricted differential duty to timely Bills of Ent...
Way Leave Permissions cannot be retrospectively revived through insolvency plans, and affected infrastructure holders require safety review and hearin...
Inter-terminal container movement requires customs escort, permit reconciliation, and indemnity, while delayed DPD cargo may move to designated CFS ya...
Business-expenditure and depreciation principles support...
Business expenditure and depreciation rules allow operational outgoings while limiting disallowances for personal elements and unsupported third-party allegations.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
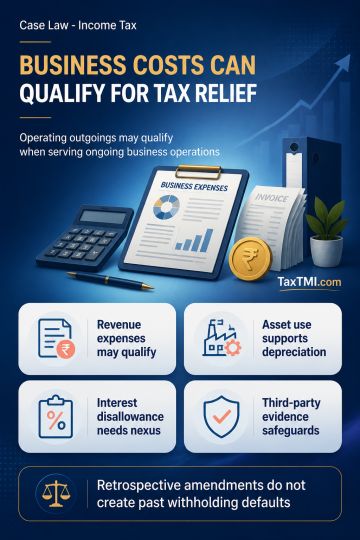
Business-expenditure and depreciation principles support deduction where expenditure serves ongoing operations without creating a capital asset or ownership right. Public-road contributions, compensatory afforestation, dry docking, mining-lease renewal stamp duty, dumping conversion charges, obsolete inventory write-offs and irrecoverable supplier advances are treated as revenue or business outgoings on the stated conditions. Depreciation is linked to use of any asset within a block and may extend to qualifying commercial vehicles, energy-saving generators and brought-forward goodwill. Interest disallowance is not justified where interest-free funds exceed investments or no borrowing-advance nexus exists. Withholding is not triggered for export-price adjustments or non-resident payments not chargeable when paid; retrospective amendments do not create past defaults. Cross-examination safeguards apply to third-party material.
Business-expenditure and depreciation principles support deduction where expenditure serves ongoing operations without creating a capital asset or ownership right. Public-road contributions, compensatory afforestation, dry docking, mining-lease renewal stamp duty, dumping conversion charges, obsolete inventory write-offs and irrecoverable supplier advances are treated as revenue or business outgoings on the stated conditions. Depreciation is linked to use of any asset within a block and may extend to qualifying commercial vehicles, energy-saving generators and brought-forward goodwill. Interest disallowance is not justified where interest-free funds exceed investments or no borrowing-advance nexus exists. Withholding is not triggered for export-price adjustments or non-resident payments not chargeable when paid; retrospective amendments do not create past defaults. Cross-examination safeguards apply to third-party material.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881