Sufficient cause for delayed revenue income-tax appeals requires bona fides, due diligence and a credible explanation; otherwise limitation bars appea...
Inverted-duty-structure refunds remain available for unchanged-rate apparel supplies despite trader status and require tax-period-specific computation...
Foundational assessment satisfaction is essential before initiating penalty for cash receipt of immovable-property sale consideration under section 27...
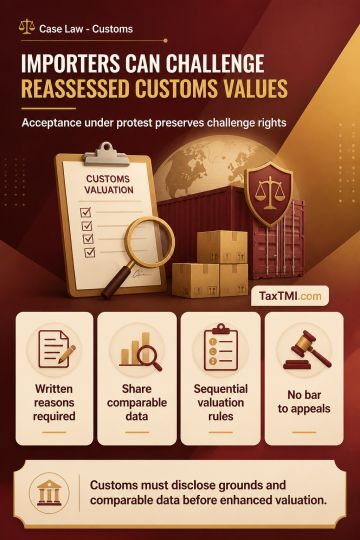
Acceptance of reassessed customs value under protest does not extinguish the importer's independent statutory right to challenge the reassessment. Written acceptance relieves the proper officer of issuing a speaking order but does not create estoppel against statutory rights in taxation. Rejection of a declared transaction value requires written communication of the grounds for doubting its truth or accuracy. Enhanced valuation cannot rest solely on undisclosed alleged contemporaneous imports; the importer must receive the relevant comparable-import data and comparability particulars. Redetermination of value must follow the prescribed sequential valuation rules after the declared value is validly rejected.
Acceptance of reassessed customs value under protest does not extinguish the importer's independent statutory right to challenge the reassessment. Written acceptance relieves the proper officer of issuing a speaking order but does not create estoppel against statutory rights in taxation. Rejection of a declared transaction value requires written communication of the grounds for doubting its truth or accuracy. Enhanced valuation cannot rest solely on undisclosed alleged contemporaneous imports; the importer must receive the relevant comparable-import data and comparability particulars. Redetermination of value must follow the prescribed sequential valuation rules after the declared value is validly rejected.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4932