Charitable sports promotion: sponsorship receipts alone did not defeat registration where funds supported tournaments and player development activitie...
Overdue associated-enterprise receivables: debt-free status defeated notional-interest adjustment, while employee stock-option costs qualified as busi...
Retrospective assessment-limitation amendments validate final orders while contemporaneous segment data governs transfer-pricing comparability and tol...
Transfer pricing adjustments must track international transactions, while unsupported AMP adjustments and unsuitable manufacturing comparables require...
Transfer-pricing adjustments must reflect functional comparability, working-capital effects, and avoid duplicating interest on associated-enterprise r...
Delayed-payment surcharge for late electricity-bill payment does...
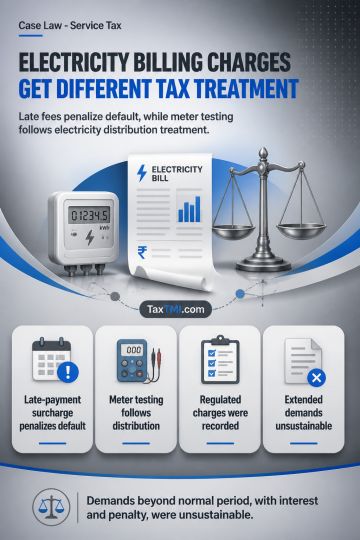
Delayed-payment surcharge is not taxable tolerance consideration where it penalises default, while meter testing follows electricity distribution treatment.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
Delayed-payment surcharge for late electricity-bill payment does not constitute consideration for tolerating an act under Section 66E(e) where it secures timely payment, discourages default and lacks an express or implied reciprocal agreement to accept delay. Meter-testing charges are ancillary to statutory electricity distribution, inseparable from consumption measurement and billing, and therefore take the negative-list treatment of the principal distribution service despite separate pricing. Extended limitation requires positive evidence of fraud, collusion, wilful misstatement, suppression or contravention intended to evade tax; publicly regulated, recorded charges previously examined by the tax authorities do not establish deliberate suppression. Consequently, demands beyond the normal period, with related interest and penalty, were unsustainable.
Delayed-payment surcharge for late electricity-bill payment does not constitute consideration for tolerating an act under Section 66E(e) where it secures timely payment, discourages default and lacks an express or implied reciprocal agreement to accept delay. Meter-testing charges are ancillary to statutory electricity distribution, inseparable from consumption measurement and billing, and therefore take the negative-list treatment of the principal distribution service despite separate pricing. Extended limitation requires positive evidence of fraud, collusion, wilful misstatement, suppression or contravention intended to evade tax; publicly regulated, recorded charges previously examined by the tax authorities do not establish deliberate suppression. Consequently, demands beyond the normal period, with related interest and penalty, were unsustainable.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881