Pre-registration physical verification becomes mandatory to prevent non-existent business registrations and support timely GST registration processing...
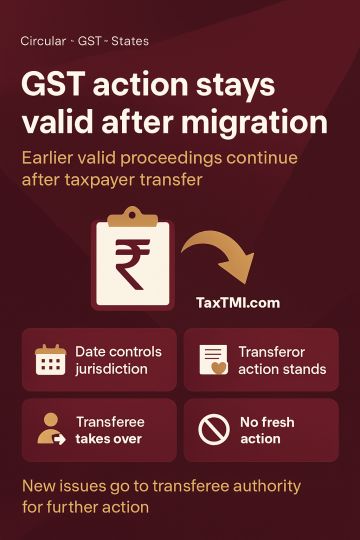
Jurisdiction under the RGST Act is determined on the date a statutory power is exercised. Actions validly undertaken by the officer having jurisdiction before a taxable person migrates to another jurisdiction remain valid and are not retrospectively invalidated. After migration, the former jurisdictional officer cannot initiate or continue action and must refer any new matter to the current jurisdictional officer. The current officer must take over pending proceedings from their existing stage, implement earlier actions, pursue consequential proceedings, and represent or conduct related appellate proceedings as though the earlier action had been initiated by that officer.
Jurisdiction under the RGST Act is determined on the date a statutory power is exercised. Actions validly undertaken by the officer having jurisdiction before a taxable person migrates to another jurisdiction remain valid and are not retrospectively invalidated. After migration, the former jurisdictional officer cannot initiate or continue action and must refer any new matter to the current jurisdictional officer. The current officer must take over pending proceedings from their existing stage, implement earlier actions, pursue consequential proceedings, and represent or conduct related appellate proceedings as though the earlier action had been initiated by that officer.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI