Prior APA methodology guides transfer pricing benchmarking where consistent FAR profiles support comparability and arm's length margins eliminate adju...
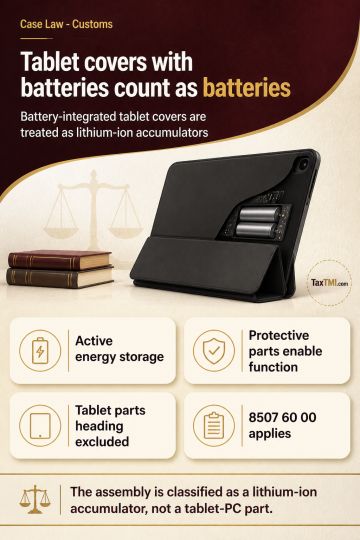
Battery-integrated tablet rear covers classify as lithium-ion accumulators when protective components enable the battery's active energy-storage funct...
Failure to verify tax deduction at source compliance on remuneration and hire expenses incurred for motion-picture production can render an assessment erroneous and prejudicial to Revenue interests. The claimed expenditure required examination of the extent of TDS deduction and deposit, while an assertion that substantial expenditure represented reimbursements required supporting records and evidence. In the absence of such verification, revisional intervention and a fresh assessment were warranted. The TDS-related expense issue was to be reconsidered after giving the assessee an opportunity of hearing.
Failure to verify tax deduction at source compliance on remuneration and hire expenses incurred for motion-picture production can render an assessment erroneous and prejudicial to Revenue interests. The claimed expenditure required examination of the extent of TDS deduction and deposit, while an assertion that substantial expenditure represented reimbursements required supporting records and evidence. In the absence of such verification, revisional intervention and a fresh assessment were warranted. The TDS-related expense issue was to be reconsidered after giving the assessee an opportunity of hearing.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881