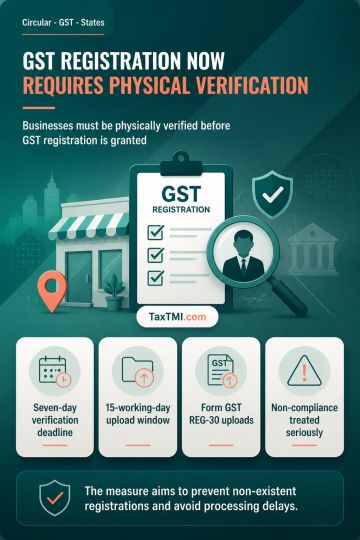
Pre-registration physical verification becomes mandatory to prevent non-existent business registrations and support timely GST registration processing...
Arm's-length pricing of interest on 30-year non-convertible debentures cannot rest on an unsupported minimum-tenure filter under the comparable uncontrolled price method, particularly where tenure does not uniformly determine coupon rates; the transfer-pricing adjustment was deleted. Interest limitation for debt payable to non-resident associated enterprises must exclude interest paid to non-associated enterprises and prevent duplicate disallowance of interest already affected by transfer pricing; recomputation and consequential relief were directed. Classification of assessment adjustments under the appropriate head of income requires verification of the computation and records. A challenge to penalty initiation is premature where no final penalty order is under appeal.
Arm's-length pricing of interest on 30-year non-convertible debentures cannot rest on an unsupported minimum-tenure filter under the comparable uncontrolled price method, particularly where tenure does not uniformly determine coupon rates; the transfer-pricing adjustment was deleted. Interest limitation for debt payable to non-resident associated enterprises must exclude interest paid to non-associated enterprises and prevent duplicate disallowance of interest already affected by transfer pricing; recomputation and consequential relief were directed. Classification of assessment adjustments under the appropriate head of income requires verification of the computation and records. A challenge to penalty initiation is premature where no final penalty order is under appeal.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881