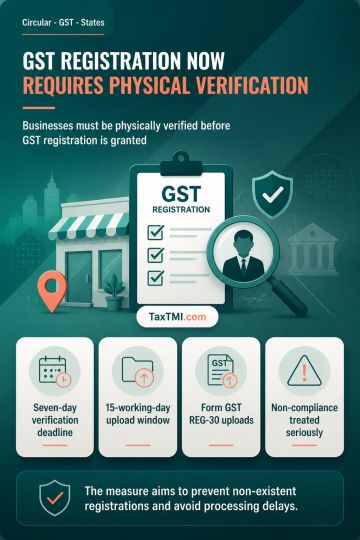
Pre-registration physical verification becomes mandatory to prevent non-existent business registrations and support timely GST registration processing...
Reassessment proceedings require the Assessing Officer to furnish recorded reasons on the taxpayer's request and dispose of objections before continuing the reassessment; non-compliance renders the reassessment unsustainable. For alleged bogus long-term capital gains, contemporaneous banking and demat records, contract notes, securities transaction tax evidence, and proof of share acquisition and sale can establish transaction genuineness. General investigation material or suspicion, without cogent evidence linking the taxpayer to accommodation entries or cash payments to an entry provider, cannot displace that evidence. Additions for unexplained share-sale proceeds and consequential alleged commission were deleted.
Reassessment proceedings require the Assessing Officer to furnish recorded reasons on the taxpayer's request and dispose of objections before continuing the reassessment; non-compliance renders the reassessment unsustainable. For alleged bogus long-term capital gains, contemporaneous banking and demat records, contract notes, securities transaction tax evidence, and proof of share acquisition and sale can establish transaction genuineness. General investigation material or suspicion, without cogent evidence linking the taxpayer to accommodation entries or cash payments to an entry provider, cannot displace that evidence. Additions for unexplained share-sale proceeds and consequential alleged commission were deleted.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881