Prior APA methodology guides transfer pricing benchmarking where consistent FAR profiles support comparability and arm's length margins eliminate adju...
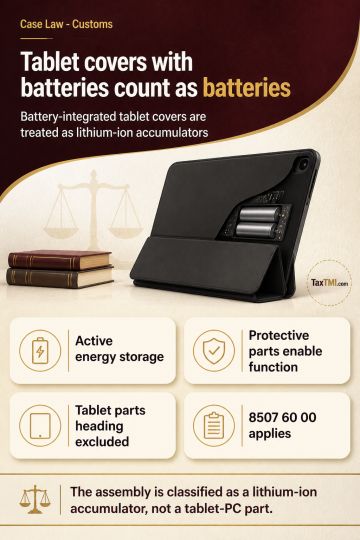
Battery-integrated tablet rear covers classify as lithium-ion accumulators when protective components enable the battery's active energy-storage funct...
Page of 4886
Press 'Enter' after typing page number.
781 to 800 of 97705 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
Tax deduction at source on leave travel concession reimbursements involving a foreign travel leg was not required where operative interim High Court directions restrained such deduction. Although the foreign travel component was not exempt, the assessee-bank was bound to comply with the interim directions and could not deduct tax contrary to them. Non-deduction during the period those directions remained operative therefore did not render the bank an assessee in default. Consequent demands for tax and interest were deleted.
Tax deduction at source on leave travel concession reimbursements involving a foreign travel leg was not required where operative interim High Court directions restrained such deduction. Although the foreign travel component was not exempt, the assessee-bank was bound to comply with the interim directions and could not deduct tax contrary to them. Non-deduction during the period those directions remained operative therefore did not render the bank an assessee in default. Consequent demands for tax and interest were deleted.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4886