Prior APA methodology guides transfer pricing benchmarking where consistent FAR profiles support comparability and arm's length margins eliminate adju...
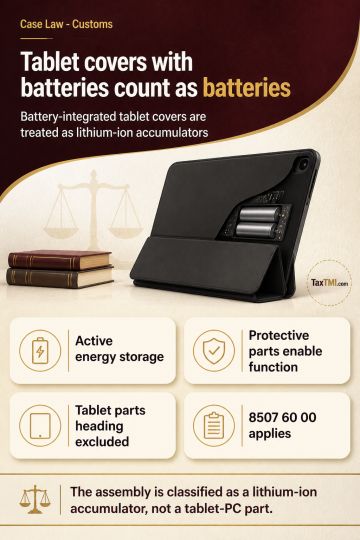
Battery-integrated tablet rear covers classify as lithium-ion accumulators when protective components enable the battery's active energy-storage funct...
Outstanding trade-creditor additions may require verification...
Tax collection at source on purchases removes duplicate withholding obligation, while trade-creditor evidence requires verification before unexplained-credit addition.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
Outstanding trade-creditor additions may require verification rather than immediate treatment as unexplained cash credits where purchases, corresponding sales and stock are accepted, repayments are undisputed, and additional evidence supports genuine dealings. Additional evidence may be admitted where a supplier's records were unavailable because of fire, subject to assessment verification; no addition should follow if verification reveals no discrepancy. For purchase transactions subject to both tax deduction and collection rules, a buyer need not deduct tax where the seller has already collected tax at source before deduction. Accordingly, the related purchase-payment disallowance was deleted, while the creditor balance was restored for verification.
Outstanding trade-creditor additions may require verification rather than immediate treatment as unexplained cash credits where purchases, corresponding sales and stock are accepted, repayments are undisputed, and additional evidence supports genuine dealings. Additional evidence may be admitted where a supplier's records were unavailable because of fire, subject to assessment verification; no addition should follow if verification reveals no discrepancy. For purchase transactions subject to both tax deduction and collection rules, a buyer need not deduct tax where the seller has already collected tax at source before deduction. Accordingly, the related purchase-payment disallowance was deleted, while the creditor balance was restored for verification.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881