Withdrawal of obsolete FEMA circulars streamlines rules on external commercial borrowings, non-resident bond investments, and money transfer sub-agent...
Departmental appeal limitation after call-book recall preserves original filing, while documented correlation supports SAD refund on imported granules...
Income-tax prosecution fails when appellate remand removes its factual foundation; directors require company arraignment for vicarious criminal liabil...
Page of 4881
Press 'Enter' after typing page number.
881 to 900 of 97618 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
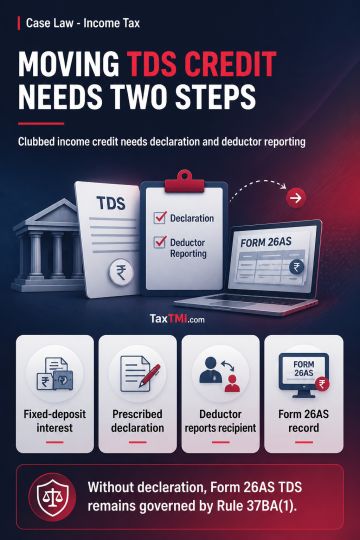
Rule 37BA(1) allocates TDS credit to the deductee based on information furnished by the deductor. Where fixed-deposit interest is assessable in a spouse's hands through clubbing of income, Rule 37BA(2) permits transfer of the related TDS credit only if the deductee gives the prescribed declaration to the deductor and the deductor reports the deduction in the other person's name. Without that declaration, TDS continuing in the deductee's Form 26AS remains governed by Rule 37BA(1). Any discrepancy between TDS claimed and the credit reflected requires examination under section 199 and Rule 37BA.
Rule 37BA(1) allocates TDS credit to the deductee based on information furnished by the deductor. Where fixed-deposit interest is assessable in a spouse's hands through clubbing of income, Rule 37BA(2) permits transfer of the related TDS credit only if the deductee gives the prescribed declaration to the deductor and the deductor reports the deduction in the other person's name. Without that declaration, TDS continuing in the deductee's Form 26AS remains governed by Rule 37BA(1). Any discrepancy between TDS claimed and the credit reflected requires examination under section 199 and Rule 37BA.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881