Foundational assessment satisfaction is essential before initiating penalty for cash receipt of immovable-property sale consideration under section 27...
Tax collection at source on purchases removes duplicate withholding obligation, while trade-creditor evidence requires verification before unexplained...
Transfer-pricing comparability requires material turnover effects; adjustments must cover only associated-enterprise transactions and exclude abnormal...
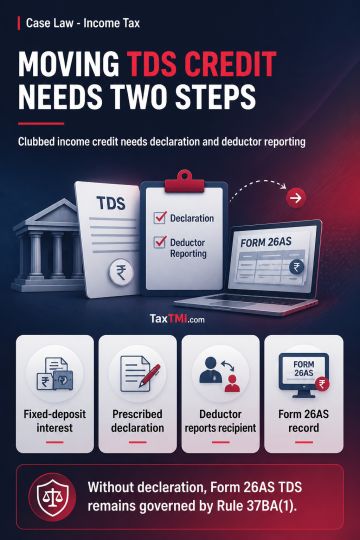
Rule 37BA(1) allocates TDS credit to the deductee based on information furnished by the deductor. Where fixed-deposit interest is assessable in a spouse's hands through clubbing of income, Rule 37BA(2) permits transfer of the related TDS credit only if the deductee gives the prescribed declaration to the deductor and the deductor reports the deduction in the other person's name. Without that declaration, TDS continuing in the deductee's Form 26AS remains governed by Rule 37BA(1). Any discrepancy between TDS claimed and the credit reflected requires examination under section 199 and Rule 37BA.
Rule 37BA(1) allocates TDS credit to the deductee based on information furnished by the deductor. Where fixed-deposit interest is assessable in a spouse's hands through clubbing of income, Rule 37BA(2) permits transfer of the related TDS credit only if the deductee gives the prescribed declaration to the deductor and the deductor reports the deduction in the other person's name. Without that declaration, TDS continuing in the deductee's Form 26AS remains governed by Rule 37BA(1). Any discrepancy between TDS claimed and the credit reflected requires examination under section 199 and Rule 37BA.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881