Effective hearing in GST adjudication requires actual opportunity to respond; ineffective service through a former auditor invalidated ex parte procee...
Third-party search material requires special assessment route, rendering general reassessment notices without jurisdiction when it forms the proceedin...
Transfer-pricing adjustments must be confined to international associated-enterprise transactions, while functionally dissimilar comparables remain ex...
Insolvency moratorium bars income-tax revision proceedings against corporate debtors until the moratorium ends, preserving merits for later determinat...
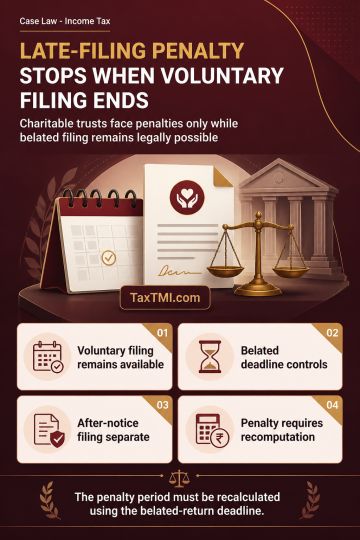
Penalty for a charitable trust's failure to file a return under section 139(4A) should run only while voluntary filing remains legally available under section 139(4). Once the belated-return period expires, the trust has no statutory right to file a valid return voluntarily; a return filed after notice under section 148 follows an independent mechanism. Treating the default as continuing after voluntary compliance becomes impossible would require performance of an impossibility. Accordingly, penalty under section 272A(2)(e) is to be recomputed by limiting the default period to the last date for filing a belated return under section 139(4).
Penalty for a charitable trust's failure to file a return under section 139(4A) should run only while voluntary filing remains legally available under section 139(4). Once the belated-return period expires, the trust has no statutory right to file a valid return voluntarily; a return filed after notice under section 148 follows an independent mechanism. Treating the default as continuing after voluntary compliance becomes impossible would require performance of an impossibility. Accordingly, penalty under section 272A(2)(e) is to be recomputed by limiting the default period to the last date for filing a belated return under section 139(4).
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881