Foundational assessment satisfaction is essential before initiating penalty for cash receipt of immovable-property sale consideration under section 27...
Tax collection at source on purchases removes duplicate withholding obligation, while trade-creditor evidence requires verification before unexplained...
Transfer-pricing comparability requires material turnover effects; adjustments must cover only associated-enterprise transactions and exclude abnormal...
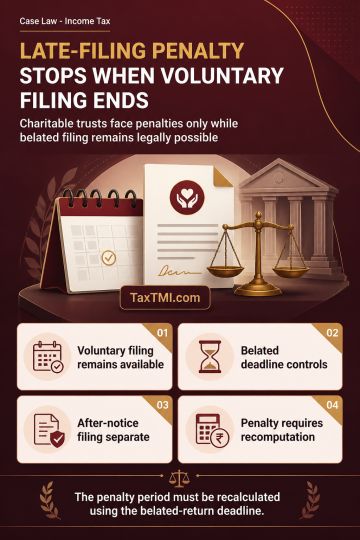
Penalty for a charitable trust's failure to file a return under section 139(4A) should run only while voluntary filing remains legally available under section 139(4). Once the belated-return period expires, the trust has no statutory right to file a valid return voluntarily; a return filed after notice under section 148 follows an independent mechanism. Treating the default as continuing after voluntary compliance becomes impossible would require performance of an impossibility. Accordingly, penalty under section 272A(2)(e) is to be recomputed by limiting the default period to the last date for filing a belated return under section 139(4).
Penalty for a charitable trust's failure to file a return under section 139(4A) should run only while voluntary filing remains legally available under section 139(4). Once the belated-return period expires, the trust has no statutory right to file a valid return voluntarily; a return filed after notice under section 148 follows an independent mechanism. Treating the default as continuing after voluntary compliance becomes impossible would require performance of an impossibility. Accordingly, penalty under section 272A(2)(e) is to be recomputed by limiting the default period to the last date for filing a belated return under section 139(4).
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881